
ATO Interpretative Decision
ATO ID 2004/445
Goods and Services Tax
GST and grouping of a company and a non-fixed trust from 1 April 2003FOI status: may be released
-
This ATO ID contains references to provisions of the A New Tax System (Goods and Services Tax) Regulations 1999, which have been replaced by the A New Tax System (Goods and Services Tax) Regulations 2019. This ATO ID continues to apply in relation to the remade Regulations.
A comparison table which provides the replacement provisions in the A New Tax System (Goods and Services Tax) Regulations 2019 for regulations which are referenced in this ATO ID is available.
Status of this decision: Decision Current from 1 April 2003. The A New Tax System (Goods and Services Tax) Regulations 1999 (amended by the A New Tax System (Goods and Services Tax) Amendment Regulations 2003 (No.1) (2003 No.37)) affects certain GST group membership requirements from 1 April 2003.
This ATOID provides you with the following level of protection:
If you reasonably apply this decision in good faith to your own circumstances (which are not materially different from those described in the decision), and the decision is later found to be incorrect you will not be liable to pay any penalty or interest. However, you will be required to pay any underpaid tax (or repay any over-claimed credit, grant or benefit), provided the time limits under the law allow it. If you do intend to apply this decision to your own circumstances, you will need to ensure that the relevant provisions referred to in the decision have not been amended or repealed. You may wish to obtain further advice from the Tax Office or from a professional adviser.
Issue
Do entity A and entity B satisfy the membership requirements of a GST group under section 48-10 of the A New Tax System (Goods and Services Tax) Act 1999 (GST Act), from 1 April 2003 when:
- •
- entity A is a company in which Individual X is the sole shareholder and director, and
- •
- entity B is a non-fixed trust of which the beneficiaries are Individual X, Individual Y and Individual Z, with both Individual Y and Individual Z being a family member of Individual X?
Decision
Yes, entity A and entity B both satisfy the membership requirements of a GST group under section 48-10 of the GST Act from 1 April 2003.
Facts
Entity A, a company, and entity B, a non-fixed trust, are both registered for goods and services tax (GST).
Entity A is a company in which Individual X is the sole shareholder and director.
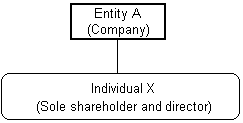
Entity B is a non-fixed trust of which the beneficiaries are Individual X, Individual Y and Individual Z. Individual Y and Individual Z are family members of Individual X.
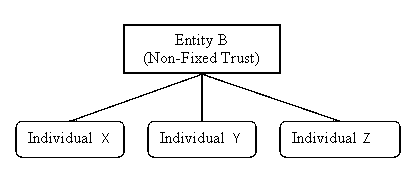
Entity B makes distributions of income and capital only to Individual X, Individual Y and Individual Z. The trustee of entity B is an unrelated company.
Entity B does not have any ownership interest in entity A. Individual X, Individual Y and Individual Z are not registered for GST.
Entity A and entity B have the same tax periods, account for GST on the same basis, are not members of any other GST group and do not have any branches which are registered under Division 54 of the GST Act.
Reasons for Decision
The membership requirements for entities to form a GST group are set out in section 48-10 of the GST Act. Some of the requirements apply to all entities. All entities must:
- •
- be registered for GST
- •
- have the same tax periods applying to it as the tax periods applying to all the other members of the GST group
- •
- account for GST on the same basis as all the other members of the GST group
- •
- not be a member of any other GST group, and
- •
- not have any branch that is registered under Division 54 of the GST Act.
Entity A and entity B are registered for GST, have the same tax periods, account for GST on the same basis, are not members of another GST group and do not have GST branches registered. Therefore, these requirements are satisfied by both entities.
However, there are additional requirements for both companies and non-fixed trusts that have to be satisfied before a GST group can be approved.
Additional membership requirements for a company
The additional membership requirements for companies are set out in section 48-10 of the GST Act. Subsection 48-10(3) of the GST Act requires a company in a GST group to satisfy the relationship requirements set out in section 48-15 of the GST Act, where one of the members of the proposed GST group is a non-company entity. Therefore, entity A, the company, must meet the relationship requirements with entity B, the non-fixed trust, set out in subsection 48-15(1) of the GST Act.
The relevant relationship requirements of subsection 48-15(1) of the GST Act are set out in paragraph 48-15(1)(e) of the GST Act which provides that a company that is a member of a GST group or a proposed GST group satisfies the relationship requirements if a trust is a member of the GST group or proposed GST group, and distributions of income or capital of the trust are not made except to an entity that is:
- (i)
- the company
- (ii)
- any other company that is a member of the GST group or proposed GST group
- (iii)
- a member of, or a family member of a member of, any company referred to in subparagraph (i) or (ii) that is a company to which subsection 48-15(1A) of the GST Act applies, or
- (iv)
- a charitable institution, a trustee of a charitable fund or a gift-deductible entity.
Entity B, the non-fixed trust, makes distributions of income and capital only to Individual X, Individual Y and Individual Z. Individual X is the only member of entity A, the company, and Individual Y and Individual Z are family members of Individual X. Therefore, as the income and capital distributions of entity B are only made to the member of, or a family member of the member of entity A, entity A will satisfy the relationship requirement in paragraph 48-15(1)(e) of the GST Act if it is a company to which subsection 48-15(1A) of the GST Act applies.
Paragraph 48-15(1A)(a) of the GST Act provides that subsection 48-15(1A) of the GST Act applies to a company if the company has only one member. Entity A is a company in which Individual X is the sole shareholder and director. As entity A only has one member, it is a company to which subsection 48-15(1A) of the GST Act applies.
Entity A satisfies paragraph 48-15(1)(e) of the GST Act. Consequently, entity A satisfies the relationship requirements with entity B under subsection 48-15(1) of the GST Act. Entity A satisfies the additional membership requirements of a GST group under section 48-10 of the GST Act.
Additional membership requirements for a non-fixed trust
The additional membership requirements for trusts are set out in the A New Tax System (Goods and Services Tax) Regulations 1999 (GST Regulations).
Regulation 48-10.03 of the GST Regulations sets out the additional requirements that must be satisfied for a trust to be a member of a GST group. This regulation was amended with effect from 1 April 2003.
Subregulation 48-10.03(1) of the GST Regulations provides that if the GST group does not consist only of fixed trusts, one of the four requirements listed in subregulation 48-10.03(2) of the GST Regulations must be satisfied by the trustee of the trust (candidate trustee) for the trust to be a member of a GST group.
Paragraph 48-10.03(2)(b) of the GST Regulations provides that the requirements are satisfied if the candidate trustee distributes any income or capital of the trust only to a beneficiary that is a 'permitted beneficiary'.
Entity B makes distributions of income and capital only to Individual X, Individual Y and Individual Z. Accordingly, if Individual X, Individual Y and Individual Z are permitted beneficiaries, then entity B will satisfy the membership requirements.
The meaning of 'permitted beneficiary' is set out in subregulations 48-10.03(3), 48-10.03(4) and 48-10.03(5) of the GST Regulations. Subregulation 48-10.03(4) of the GST Regulations provides that for a company that is a member of the GST group, each representative of a shareholder of the company is also a permitted beneficiary if, for a company with 1 shareholder - the beneficiaries of the trust include a representative of the shareholder.
Regulation 48-10.01 of the GST Regulations defines 'representative' in relation to an individual shareholder in a company, as the shareholder or a family member of the shareholder. Individual X is the sole shareholder of entity A. Both Individual Y and Individual Z are family members of Individual X. Therefore, Individual X, Individual Y and Individual Z all satisfy the definition of a 'representative' of entity A, for the purposes of regulation 48-10.01 of the GST Regulations.
Accordingly, as Individual X, Individual Y and Individual Z are all beneficiaries of entity B, and are also representatives of entity A, they are all a 'permitted beneficiary' for the purposes of subregulation 48-10.03(4) of the GST Regulations.
As entity B is distributing income or capital only to beneficiaries that are permitted beneficiaries, subregulation 48-10.03(2) of the GST Regulations is satisfied. Therefore, entity B meets the additional membership requirements to be a member of a GST group under regulation 48-10.03 of the GST Regulations.
Entity A and the entity B both satisfy the membership requirements to form a GST group under section 48-10 of the GST Act.
Date of decision: 23 December 2003
Legislative References:
A New Tax System (Goods and Services Tax) Act 1999
section 48-10
subsection 48-10(3)
section 48-15
subsection 48-15(1)
paragraph 48-15(1)(e)
subsection 48-15(1A)
paragraph 48-15(1A)(a)
Division 54
regulation 48-10.01
regulation 48-10.03
subregulation 48-10.03(1)
subregulation 48-10.03(2)
paragraph 48-10.03(2)(b)
subregulation 48-10.03(3)
subregulation 48-10.03(4)
subregulation 48-10.03(5)
Keywords
Goods and services tax
GST special rules
GST groups
GST regulations
GST tax periods
ISSN: 1445-2782
Copyright notice
© Australian Taxation Office for the Commonwealth of Australia
You are free to copy, adapt, modify, transmit and distribute material on this website as you wish (but not in any way that suggests the ATO or the Commonwealth endorses you or any of your services or products).
