Medicare Levy Act 1986
Where a person: (a) is a married person on the last day of the year of income; or (b) is entitled to a tax offset under Subdivision 61-A of the Income Tax Assessment Act 1997 for the year of income in respect of the person ' s child (within the meaning of that Act); or (c) is entitled to a notional tax offset under Subdivision 961-B of the Income Tax Assessment Act 1997 for the year of income;
(d) (Repealed by No 70 of 2015)
and the family income in relation to the person does not exceed the family income threshold in relation to the person, no levy is payable by the person upon the taxable income of the person.
 Hide history note
 View history note
S 8(1) amended by No 70 of 2015, s 3 and Sch 2 item 30, by substituting para (b) and (c) for para (b), (c) and (d), applicable in relation to assessments for the 2014-15 income year and later income years. Para (b), (c) and (d) formerly read:
(b) is entitled to a rebate under section 159J of the Assessment Act in respect of a person included in class 2 of the table in subsection 159J(2) of that Act, or would be so entitled apart from subsection 159J(1AB) or 159JA(1) of that Act; or
(c) would be entitled to a rebate under section 159K of that Act in respect of the year of income, apart from subsection 159K(1A) of that Act; or
(d) is entitled to a rebate under section 159L of that Act, or would be so entitled apart from subsection 159L(3B) or 159LA(1) of that Act;
S 8(1) amended by No 105 of 2010, s 3 and Sch 1 items 54 and 55, by substituting " subsection 159J(1AB) or 159JA(1) " for " subsection 159J(1AA) or (1AB) " in para (b) and " subsection 159L(3B) or 159LA(1) " for " subsection 159L(3A) or (3B) " in para (d), effective 1 October 2010.
S 8(1) amended by No 63 of 2008, s 3 and Sch 1 items 12 and 13, by inserting " or (1AB) " after " subsection 159J(1AA) " in para (b) and inserting " or (3B) " after " subsection 159L(3A) " in para (d), applicable in relation to the 2008-09 income year and later income years.
S 8(1) amended by No 39 of 2002, No 82 of 1999 and No 135 of 1990.
8(2)
Subject to subsection (3) , where a person (in this subsection referred to as the relevant person ): (a) was a married person on the last day of the year of income; or (b) is entitled to a tax offset under Subdivision 61-A of the Income Tax Assessment Act 1997 for the year of income in respect of the person ' s child (within the meaning of that Act); or (c) is entitled to a notional tax offset under Subdivision 961-B of the Income Tax Assessment Act 1997 for the year of income;
(d) (Repealed by No 70 of 2015)
and the family income in relation to the relevant person exceeds the family income threshold in relation to the relevant person, the amount of the levy payable by the relevant person upon the taxable income of the relevant person but for this section and section 9 shall be reduced by the amount (if any) calculated in accordance with the formula:
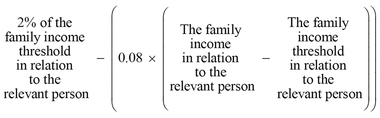
S 8(2) amended by No 70 of 2015, s 3 and Sch 2 item 31, by substituting para (b) and (c) for para (b), (c) and (d), applicable in relation to assessments for the 2014-15 income year and later income years. Para (b), (c) and (d) formerly read:
(b) is entitled to a rebate under section 159J of the Assessment Act in respect of a person included in class 2 of the table in subsection 159J(2) of that Act, or would be so entitled apart from subsection 159J(1AB) or 159JA(1) of that Act; or
(c) would be entitled to a rebate under section 159K of that Act in respect of the year of income, apart from subsection 159K(1A) of that Act; or
(d) is entitled to a rebate under section 159L of that Act, or would be so entitled apart from subsection 159L(3B) or 159LA(1) of that Act;
S 8(2) amended by No 43 of 2013, s 3 and Sch 1 items 5 - 6, by substituting the formula and omitting all the words after the formula, applicable to assessments for the 2014-15 year of income and later years of income. The formula formerly read:
A − (0.085 ( B − C ))
The words formerly read:
where:
A is 1.5% of the family income threshold in relation to the relevant person;
B is the family income in relation to the relevant person; and
C is the family income threshold in relation to the relevant person.
S 8(2) amended by No 105 of 2010, s 3 and Sch 1 items 56 and 57, by substituting " subsection 159J(1AB) or 159JA(1) " for " subsection 159J(1AA) or (1AB) " in para (b) and " subsection 159L(3B) or 159LA(1) " for " subsection 159L(3A) or (3B) " in para (d), effective 1 October 2010.
S 8(2) amended by No 63 of 2008, s 3 and Sch 1 items 14 and 15, by inserting " or (1AB) " after " subsection 159J(1AA) " in para (b) and inserting " or (3B) " after " subsection 159L(3A) " in para (d), applicable in relation to the 2008-09 income year and later income years.
S 8(2) amended by No 55 of 2006, s 3 and Sch 4 item 6, by substituting the formula, applicable to assessments for the 2006-07 year of income and later years of income. The formula formerly read:
A - (0.185 ( B - C))
S 8(2) amended by No 39 of 2002, No 82 of 1999, No 16 of 1996, No 56 of 1995, No 157 of 1992, No 135 of 1990 and No 110 of 1987.
8(3)
Where: (a) but for this subsection, the amount of levy payable by a person upon the taxable income of the person but for this section and section 9 would be reduced by an amount (in this subsection referred to as the reduction amount ) ascertained in accordance with subsection (2) ; (b) the person was a married person on the last day of the year of income; and (c) but for this section and section 9 , the spouse of the person would be liable to pay levy upon the taxable income of the spouse;
the reduction amount shall, subject to subsection (4) , be reduced by so much of the reduction amount as bears to the reduction amount the same proportion as the amount of the taxable income of the spouse bears to the family income in relation to the person.
S 8(3)(b) amended by No 135 of 1990.
8(4)
Where: (a) subsection (3) applies for the purposes of ascertaining the levy payable by a person upon the taxable income of the person but for section 9 ; and (b) the amount of the reduction of that levy ascertained in accordance with subsections (2) and (3) exceeds the amount of the levy payable by the person upon the taxable income of the person but for this section and section 9 ;
the amount of levy payable by the spouse of the person upon the taxable income of the spouse but for this subsection and section 9 shall be reduced by the amount of the excess.
8(5)
In this section:
family income
, in relation to a person, means:
(a) if the person was a married person on the last day of the year of income - the sum of the taxable income of the person and the taxable income of the spouse of the person; and
(b) in any other case - the taxable income of the person.
Definition of " family income " amended by No 135 of 1990.
family income threshold
, in relation to a person (the
relevant person
), means
$
47,238 increased by
$
4,338 for each person covered by paragraph
961-5(1)(c)
of the
Income Tax Assessment Act 1997
in respect of whom:
(a) in a case to which paragraph (b) does not apply - the relevant person; or
(b) if the relevant person was a married person on the last day of the year of income - the relevant person or the spouse of the relevant person;
is entitled to a notional tax offset under Subdivision 961-A of the Income Tax Assessment Act 1997 for the year of income.
Definition of " family income threshold " amended by No 58 of 2026, s 3 and Sch 5 items 6 and 7, by substituting " $ 47,238 " for " $ 45,907 " and " $ 4,338 " for " $ 4,216 " , effective 1 July 2026 and applicable in relation to assessments for the 2025-26 year of income and later years of income.
Definition of " family income threshold " amended by No 28 of 2025, s 3 and Sch 2 items 6 and 7, by substituting " $ 45,907 " for " $ 43,846 " and " $ 4,216 " for " $ 4,027 " , effective 28 March 2025 and applicable in relation to assessments for the 2024-25 year of income and later years of income.
Definition of " family income threshold " amended by No 4 of 2024, s 3 and Sch 1 items 6 and 7, by substituting " $ 43,846 " for " $ 40,939 " and " $ 4,027 " for " $ 3,760 " , effective 6 March 2024 and applicable in relation to assessments for the 2023-24 year of income and later years of income.
Definition of " family income threshold " amended by No 28 of 2023, s 3 and Sch 1 items 6 and 7, by substituting " $ 40,939 " for " $ 39,402 " and " $ 3,760 " for " $ 3,619 " , effective 24 June 2023 and applicable to assessments for the 2022-23 year of income and later years of income.
Definition of " family income threshold " amended by No 14 of 2022, s 3 and Sch 1 items 6 and 7, by substituting " $ 39,402 " for " $ 39,167 " and $ 3,619 " for " $ 3,597 " , effective 1 April 2022 and applicable to assessments for the 2021-22 year of income and later years of income.
Definition of " family income threshold " amended by No 61 of 2021, s 3 and Sch 1 items 6 and 7, by substituting " $ 39,167 " for " $ 38,474 " and " $ 3,597 " for " $ 3,533 " , effective 30 June 2021 and applicable to assessments for the 2020-21 year of income and later years of income.
Definition of " family income threshold " amended by No 22 of 2020, s 3 and Sch 14 items 6 and 7, by substituting " $ 38,474 " for " $ 37,794 " and " $ 3,533 " for " $ 3,471 " , effective 25 March 2020 and applicable to assessments for the 2019-20 year of income and later years of income.
Definition of " family income threshold " amended by No 29 of 2019, s 3 and Sch 1 items 6 and 7, by substituting " $ 37,794 " for " $ 37,089 " and " $ 3,471 " for " $ 3,406 " , effective 6 April 2019 and applicable to assessments for the 2018-19 year of income and later years of income.
Definition of " family income threshold " amended by No 69 of 2018, s 3 and Sch 1 items 6 and 7, by substituting " $ 37,089 " for " $ 36,541 " and " $ 3,406 " for " $ 3,356 " , applicable to assessments for the 2017-18 year of income and later years of income.
Definition of " family income threshold " amended by No 58 of 2017, s 3 and Sch 1 items 6 and 7, by substituting " $ 36,541 " for " $ 36,001 " and " $ 3,356 " for " $ 3,306 " , applicable to assessments for the 2016-17 year of income and later years of income.
Definition of " family income threshold " amended by No 39 of 2016, s 3 and Sch 1 items 6 and 7, by substituting " $ 36,001 " for " $ 35,261 " and " $ 3,306 " for " $ 3,238 " , applicable to assessments for the 2015-16 year of income and later years of income.
Definition of " family income threshold " substituted by No 70 of 2015, s 3 and Sch 2 item 32, applicable in relation to assessments for the 2014-15 income year and later income years. The definition formerly read:
family income threshold
, in relation to a person (in this definition referred to as the relevant person ), means $ 35,261 increased by $ 3,238 for each person included in class 3 or class 4 in the table in subsection 159J(2) of the Assessment Act in respect of whom:
(a) in a case to which paragraph (b) does not apply - the relevant person; or
(b) if the relevant person was a married person on the last day of the year of income - the relevant person or the spouse of the relevant person;would, but for subsections 159J(1A) and (1F) of the Assessment Act, be entitled to a rebate of tax under section 159J of the Assessment Act in respect of the year of income.
Definition of " family income threshold " amended by No 69 of 2015, s 3 and Sch 1 items 6 and 7, by substituting " $ 35,261 " for " $ 34,367 " and " $ 3,238 " for " $ 3,156 " , applicable to assessments for the 2014-15 year of income and later years of income.
Definition of " family income threshold " amended by No 68 of 2014, s 3 and Sch 1 item 4, by substituting " subsections 159J(1A) and (1F) " for " subsection 159J(1A) " , applicable to assessments for the 2012-13 year of income and later years of income.
Definition of " family income threshold " amended by No 68 of 2014, s 3 and Sch 1 items 2 and 3, by substituting " $ 34,367 " for " $ 33,693 " and " $ 3,156 " for " $ 3,094 " , applicable to assessments for the 2013-14 year of income and later years of income.
Definition of " family income threshold " amended by No 81 of 2013, s 3 and Sch 1 items 1 and 2, by substituting " $ 33,693 " for " $ 32,743 " and " $ 3,094 " for " $ 3,007 " , applicable to assessments for the 2012-2013 year of income and later years of income.
Definition of " family income threshold " amended by No 86 of 2012, s 3 and Sch 1 items 6 and 7, by substituting " $ 32,743 " for " $ 31,789 " and " $ 3,007 " for " $ 2,919 " , applicable to assessments for the 2011-2012 year of income.
Definition of " family income threshold " amended by No 44 of 2011, s 3 and Sch 1 items 6 and 7, by substituting " $ 31,789 " for " $ 31,196 " and " $ 2,919 " for " $ 2,865 " , applicable to assessments for the 2010-11 year of income and later years of income.
Definition of " family income threshold " amended by No 78 of 2010 , s 3 and Sch 1 items 6 and 7, by substituting " $ 31,196 " for " $ 30,025 " and substituting " $ 2,865 " for " $ 2,757 " , applicable to assessments for the 2009-10 year of income and later years of income.
Definition of " family income threshold " amended by No 41 of 2009, s 3 and Sch 1 items 6 and 7, by substituting " $ 30,025 " for " $ 29,207 " and " $ 2,757 " for " $ 2,682 " , applicable to assessments for the 2008-09 year of income and later years of income.
Definition of " family income threshold " amended by No 50 of 2008 , s 3 and Sch 1 items 6 and 7, by substituting " $ 29,207 " for " $ 28,247 " and substituting " $ 2,682 " for " $ 2,594 " , applicable to assessments for the 2007-08 year of income and later years of income.
Definition of " family income threshold " amended by No 75 of 2007, s 3 and Sch 1 items 19 and 20, by substituting " $ 28,247 " for " $ 27,478 " and " $ 2,594 " for " $ 2,523 " , applicable to assessments for the 2006-2007 year of income and later years of income.
Definition of " family income threshold " amended by No 59 of 2006, s 3 and Sch 1 items 6 and 7, by substituting " $ 27,478 " for " $ 26,834 " and " $ 2,523 " for " $ 2,464 " , applicable to assessments for the 2005-2006 year of income and later years of income.
Definition of " family income threshold " amended by No 62 of 2005, No 84 of 2004, No 67 of 2003, No 39 of 2002, No 12 of 2001, No 54 of 2000, No 29 of 1998, No 64 of 1997, No 56 of 1995, No 57 of 1993, No 155 of 1992, No 212 of 1991, No 135 of 1990, No 86 of 1990, No 137 of 1989, No 93 of 1988 and No 110 of 1987.
8(6)
In the application of the definition of family income threshold in subsection (5) in determining the family income threshold in relation to a person in relation to a year of income, being a person who was not a married person on the last day of the year of income, the amount of $ 47,238 referred to in that definition shall not be increased on account of another person unless family tax benefit under the A New Tax System (Family Assistance) (Administration) Act 1999 was payable to the first-mentioned person in respect of that other person in respect of the whole or any part of the year of income.
S 8(6) amended by No 58 of 2026, s 3 and Sch 5 item 8, by substituting " $ 47,238 " for " $ 45,907 " , effective 1 July 2026 and applicable in relation to assessments for the 2025-26 year of income and later years of income.
S 8(6) amended by No 28 of 2025, s 3 and Sch 2 item 8, by substituting " $ 45,907 " for " $ 43,846 " , effective 28 March 2025 and applicable in relation to assessments for the 2024-25 year of income and later years of income.
S 8(6) amended by No 4 of 2024, s 3 and Sch 1 item 8, by substituting " $ 43,846 " for " $ 40,939 " , effective 6 March 2024 and applicable in relation to assessments for the 2023-24 year of income and later years of income.
S 8(6) amended by No 28 of 2023, s 3 and Sch 1 item 8, by substituting " $ 40,939 " for " $ 39,402 " , effective 24 June 2023 and applicable to assessments for the 2022-23 year of income and later years of income.
S 8(6) amended by No 14 of 2022, s 3 and Sch 1 item 8, by substituting " $ 39,402 " for " $ 39,167 " , effective 1 April 2022 and applicable to assessments for the 2021-22 year of income and later years of income.
S 8(6) amended by No 61 of 2021, s 3 and Sch 1 item 8, by substituting " $ 39,167 " for " $ 38,474 " , effective 30 June 2021 and applicable to assessments for the 2020-21 year of income and later years of income.
S 8(6) amended by No 22 of 2020, s 3 and Sch 14 item 8, by substituting " $ 38,474 " for " $ 37,794 " , effective 25 March 2020 and applicable to assessments for the 2019-20 year of income and later years of income.
S 8(6) amended by No 29 of 2019, s 3 and Sch 1 item 8, by substituting " 37,794 " for " $ 37,089 " , effective 6 April 2019 and applicable to assessments for the 2018-19 year of income and later years of income.
S 8(6) amended by No 69 of 2018, s 3 and Sch 1 item 8, by substituting " $ 37,089 " for " $ 36,541 " , applicable to assessments for the 2017-18 year of income and later years of income.
S 8(6) amended by No 58 of 2017, s 3 and Sch 1 item 8, by substituting " $ 36,541 " for " $ 36,001 " , applicable to assessments for the 2016-17 year of income and later years of income.
S 8(6) amended by No 39 of 2016, s 3 and Sch 1 item 8, by substituting " $ 36,001 " for " $ 35,261 " , applicable to assessments for the 2015-16 year of income and later years of income.
S 8(6) amended by No 69 of 2015, s 3 and Sch 1 item 8, by substituting " $ 35,261 " for " $ 34,367 " , applicable to assessments for the 2014-15 year of income and later years of income.
S 8(6) amended by No 68 of 2014, s 3 and Sch 1 item 5, by substituting " $ 34,367 " for " $ 33,693 " , applicable to assessments for the 2013-14 year of income and later years of income.
S 8(6) amended by No 81 of 2013, s 3 and Sch 1 item 3, by substituting " $ 33,693 " for " $ 32,743 " , applicable to assessments for the 2012-2013 year of income and later years of income.
S 8(6) amended by No 86 of 2012, s 3 and Sch 1 item 8, by substituting " $ 32,743 " for " $ 31,789 " , applicable to assessments for the 2011-2012 year of income.
S 8(6) amended by No 44 of 2011, s 3 and Sch 1 item 8, by substituting " $ 31,789 " for " $ 31,196 " , applicable to assessments for the 2010-11 year of income and later years of income.
S 8(6) amended by No 78 of 2010 , s 3 and Sch 1 item 8, by substituting " $ 31,196 " for " $ 30,025 " , applicable to assessments for the 2009-10 year of income and later years of income.
S 8(6) amended by No 41 of 2009, s 3 and Sch 1 item 8, by substituting " $ 30,025 " for " $ 29,207 " , applicable to assessments for the 2008-09 year of income and later years of income.
S 8(6) amended by No 50 of 2008 , s 3 and Sch 1 item 8, by substituting " $ 29,207 " for " $ 28,247 " , applicable to assessments for the 2007-08 year of income and later years of income.
S 8(6) amended by No 75 of 2007, s 3 and Sch 1 item 21, by substituting " $ 28,247 " for " $ 27,478 " , applicable to assessments for the 2006-2007 year of income and later years of income.
S 8(6) amended by No 59 of 2006, s 3 and Sch 1 item 8, by substituting " $ 27,478 " for " $ 26,834 " , applicable to assessments for the 2005-2006 year of income and later years of income.
S 8(6) amended by No 62 of 2005, No 84 of 2004, No 67 of 2003, No 39 of 2002, No 12 of 2001, No 54 of 2000, No 83 of 1999, No 93 of 1998, No 29 of 1998, No 64 of 1997, No 56 of 1995, No 57 of 1993, No 157 of 1992, No 155 of 1992, No 212 of 1991, No 100 of 1991, No 135 of 1990, No 86 of 1990, No 137 of 1989, No 93 of 1988 and No 110 of 1987.
[ CCH Note: S 8(6) was amended by No 29 of 2019, s 3 and Sch 1 item 8, by substituting " 37,794 " for " $ 37,089 " . This amendment has been editorially changed to insert a " $ " before " 37,794 " to correct this typographical error, in line with an editorial change made by the Federal Register of Legislation under the Legislation Act 2003 .]
8(7)
Subsections (5) and (6) apply in relation to a person who is entitled for the year of income to a rebate under section 160AAAA of the Assessment Act as if each reference to $ 47,238 were a reference to $ 61,623.
S 8(7) amended by No 58 of 2026, s 3 and Sch 5 items 8 and 9, by substituting " $ 47,238 " for " $ 45,907 " and " $ 61,623 " for " $ 59,886 " , effective 1 July 2026 and applicable in relation to assessments for the 2025-26 year of income and later years of income.
S 8(7) amended by No 28 of 2025, s 3 and Sch 2 items 8 and 9, by substituting " $ 45,907 " for " $ 43,846 " and " $ 59,886 " for " $ 57,198 " , effective 28 March 2025 and applicable in relation to assessments for the 2024-25 year of income and later years of income.
S 8(7) amended by No 4 of 2024, s 3 and Sch 1 items 8 and 9, by substituting " $ 43,846 " for " $ 40,939 " and " $ 57,198 " for " $ 53,406 " , effective 6 March 2024 and applicable in relation to assessments for the 2023-24 year of income and later years of income.
S 8(7) amended by No 28 of 2023, s 3 and Sch 1 items 8 and 9, by substituting " $ 40,939 " for " $ 39,402 " and " $ 53,406 " for " $ 51,401 " , effective 24 June 2023 and applicable to assessments for the 2022-23 year of income and later years of income.
S 8(7) amended by No 14 of 2022, s 3 and Sch 1 items 8 and 9, by substituting " $ 39,402 " for " $ 39,167 " and " $ 51,401 " for " $ 51,094 " , effective 1 April 2022 and applicable to assessments for the 2021-22 year of income and later years of income.
S 8(7) amended by No 61 of 2021, s 3 and Sch 1 items 8 and 9, by substituting " $ 39,167 " for " $ 38,474 " and " $ 51,094 " for " $ 50,191 " , effective 30 June 2021 and applicable to assessments for the 2020-21 year of income and later years of income.
S 8(7) amended by No 22 of 2020, s 3 and Sch 14 items 8 and 9, by substituting " $ 38,474 " for " $ 37,794 " and " $ 50,191 " for " $ 49,304 " , effective 25 March 2020 and applicable to assessments for the 2019-20 year of income and later years of income.
S 8(7) amended by No 29 of 2019, s 3 and Sch 1 items 8 and 9, by substituting " 37,794 " for " $ 37,089 " and " $ 49,304 " for " $ 48,385 " , effective 6 April 2019 and applicable to assessments for the 2018-19 year of income and later years of income.
S 8(7) amended by No 69 of 2018, s 3 and Sch 1 items 8 and 9, by substituting " $ 37,089 " for " $ 36,541 " and " $ 48,385 " for " $ 47,670 " , applicable to assessments for the 2017-18 year of income and later years of income.
S 8(7) amended by No 58 of 2017, s 3 and Sch 1 items 8 and 9, by substituting " $ 36,541 " for " $ 36,001 " and " $ 47,670 " for " $ 46,966 " , applicable to assessments for the 2016-17 year of income and later years of income.
S 8(7) amended by No 39 of 2016, s 3 and Sch 1 items 8 and 9, by substituting " $ 36,001 " for " $ 35,261 " and " $ 46,966 " for " $ 46,000 " , applicable to assessments for the 2015-16 year of income and later years of income.
S 8(7) amended by No 69 of 2015, s 3 and Sch 1 item 8, by substituting " $ 35,261 " for " $ 34,367 " , applicable to assessments for the 2014-15 year of income and later years of income.
S 8(7) amended by No 68 of 2014, s 3 and Sch 1 item 5, by substituting " $ 34,367 " for " $ 33,693 " , applicable to assessments for the 2013-14 year of income and later years of income.
S 8(7) amended by No 81 of 2013, s 3 and Sch 1 item 3, by substituting " $ 33,693 " for " $ 32,743 " , applicable to assessments for the 2012-2013 year of income and later years of income.
S 8(7) amended by No 86 of 2012, s 3 and Sch 1 item 8, by substituting " $ 32,743 " for " $ 31,789 " , applicable to assessments for the 2011-2012 year of income.
S 8(7) amended by No 159 of 2011, s 3 and Sch 2 item 6, by substituting " $ 46,000 " for " $ 44,500 " , applicable to the 2012-13 year of income and later years of income.
S 8(7) amended by No 44 of 2011, s 3 and Sch 1 item 8, by substituting " $ 31,789 " for " $ 31,196 " , applicable to assessments for the 2010-11 year of income and later years of income.
S 8(7) amended by No 29 of 2008 , s 3 and Sch 1 item 29, by substituting " $ 44,500 " for " $ 43,500 " , applicable to assessments for the 2010-11 year of income and later years of income.
S 8(7) amended by No 78 of 2010 , s 3 and Sch 1 item 8, by substituting " $ 31,196 " for " $ 30,025 " , applicable to assessments for the 2009-10 year of income and later years of income.
S 8(7) amended by No 41 of 2009, s 3 and Sch 1 item 8, by substituting " $ 30,025 " for " $ 29,207 " , applicable to assessments for the 2008-09 year of income and later years of income.
S 8(7) amended by No 50 of 2008 , s 3 and Sch 1 item 8, by substituting " $ 29,207 " for " $ 28,247 " , applicable to assessments for the 2007-08 year of income and later years of income.
S 8(7) amended by No 29 of 2008 , s 3 and Sch 1 item 19, by substituting " $ 43,500 " for " $ 42,000 " , applicable to assessments for the 2009-10 year of income.
S 8(7) amended by No 29 of 2008 , s 3 and Sch 1 item 9, by substituting " $ 42,000 " for " $ 37,950 " , applicable to assessments for the 2008-09 year of income.
S 8(7) amended by No 76 of 2007, s 3 and Sch 1 item 10, by substituting " $ 37,950 " for " $ 33,500 " , applicable to assessments for the 2007-08 year of income and later years of income.
S 8(7) amended by No 75 of 2007, s 3 and Sch 1 item 21, by substituting " $ 28,247 " for " $ 27,478 " , applicable to assessments for the 2006-2007 year of income and later years of income.
S 8(7) amended by No 59 of 2006, s 3 and Sch 1 item 8, by substituting " $ 27,478 " for " $ 26,834 " , applicable to assessments for the 2005-2006 year of income and later years of income.
S 8(7) amended by No 55 of 2006, s 3 and Sch 4 item 7, by substituting " $ 33,500 " for " $ 31,729 " , applicable to assessments for the 2006-07 year of income and later years of income.
S 8(7) amended by No 62 of 2005, No 84 of 2004, No 67 of 2003, No 39 of 2002 and inserted by No 44 of 2001.
[ CCH Note: S 8(7) was amended by No 29 of 2019, s 3 and Sch 1 item 8, by substituting " 37,794 " for " $ 37,089 " . This amendment has been editorially changed to insert a " $ " before " 37,794 " to correct this typographical error, in line with an editorial change made by the Federal Register of Legislation under the Legislation Act 2003 .]
Disclaimer and notice of copyright applicable to materials provided by CCH Australia Limited
CCH Australia Limited ("CCH") believes that all information which it has provided in this site is accurate and reliable, but gives no warranty of accuracy or reliability of such information to the reader or any third party. The information provided by CCH is not legal or professional advice. To the extent permitted by law, no responsibility for damages or loss arising in any way out of or in connection with or incidental to any errors or omissions in any information provided is accepted by CCH or by persons involved in the preparation and provision of the information, whether arising from negligence or otherwise, from the use of or results obtained from information supplied by CCH.
The information provided by CCH includes history notes and other value-added features which are subject to CCH copyright. No CCH material may be copied, reproduced, republished, uploaded, posted, transmitted, or distributed in any way, except that you may download one copy for your personal use only, provided you keep intact all copyright and other proprietary notices. In particular, the reproduction of any part of the information for sale or incorporation in any product intended for sale is prohibited without CCH's prior consent.
