Product Ruling
PR 2026/21
FTC Automator platform - use by clients of KPMG and Directed Australia to calculate fuel tax credits
-
Please note that the PDF version is the authorised version of this ruling.
| Table of Contents | Paragraph |
|---|---|
| What this Ruling is about | |
| Who this Ruling applies to | |
| Qualifications | |
| Date of effect | |
| Ruling | |
| Assumptions | |
| Scheme | |
| Overview of the Scheme | |
| Appendix – Explanation |
 Relying on this Ruling This publication (excluding appendix) is a public ruling for the purposes of the Taxation Administration Act 1953. If this Ruling applies to you, and you correctly rely on it, we will apply the law to you in the way set out in this Ruling. That is, you will not pay any more tax or penalties or interest in respect of the matters covered by this Ruling. |
|
Terms of use of this Ruling
This Ruling has been given on the basis that the entity who applied for the Ruling, and their associates, will abide by strict terms of use. Any failure to comply with the terms of use may lead to the withdrawal of this Ruling. Changes in the law Product Rulings were introduced for the purpose of providing certainty about tax consequences for entities in schemes such as this. In keeping with that intention, the Commissioner suggests promoters and advisers ensure that participants are fully informed of any legislative changes after the Ruling has issued. Similarly, entities that are considering participating in the scheme are advised to confirm with their tax adviser that changes in the law have not affected this Ruling since it was issued. No guarantee of commercial success The Commissioner does not sanction or guarantee this product. Further, the Commissioner gives no assurance that the product is commercially viable, that charges are reasonable, appropriate or represent industry norms, or that projected returns will be achieved or are reasonably based. Potential participants must form their own view about the commercial and financial viability of the product. The Commissioner recommends a financial (or other) adviser be consulted for such information. |
1. This Ruling sets out the fuel tax credit consequences for fuel tax credit clients of KPMG and Directed Australia (Directed) that use the FTC Automator platform (FTC Automator).
2. All legislative references in this Ruling are to the Fuel Tax Act 2006, unless otherwise indicated. This Ruling does not address the assessability of fuel tax credits for income tax purposes or other taxation obligations.
3. The FTC Automator is a telematics technology-based fuel tax credits product, designed to support apportionment, perform calculations, and generate reports. FTC Automator gathers a range of information and data that can be sourced from Global Navigation Satellite Systems (GNSS), including Global Positioning System (GPS), and telematics technology.
4. The FTC Automator can process data from various sources. For the purposes of this Ruling, it applies only to vehicles equipped with telematics and GPS data sourced from devices provided by Directed[1], together with services delivered by KPMG. The FTC Automator captures direct measurement of fuel use from telematics data ingested and has no assumptions or derivation. It does not rely on fuel consumption rates, time, or any other estimation method.
5. Broadly, and subject to paragraphs 16 to 102 of this Ruling, this Ruling addresses whether the:
- •
- FTC Automator provides a step in the apportionment of fuel
- •
- apportionment methodology used is fair and reasonable
- •
- FTC Automator generates fair and reasonable results to work out the amount of fuel tax credits to be included in the calculation of the net fuel amount
- •
- FTC Automator has governance and assurance processes (including exception indicators and safeguard rules) in place to identify and correct any outliers and errors, including fuel consumption rates, and
- •
- FTC Report can be used for fuel tax credit record-keeping purposes.
6. This Ruling applies to you if you are registered for goods and services tax and:
- •
- are fuel tax credit clients (clients) that elect to receive ongoing fuel tax credit advice from KPMG in relation to the fuel tax credit results generated by FTC Automator, based on telematics and GPS data generated by Directed
- •
- have acquired taxable fuel on or after 1 January 2025 to 31 December 2028
- •
- are using the FTC Automator for apportioning that taxable fuel acquired and used in vehicles and auxiliary equipment in carrying on your enterprise for fuel tax credit purposes.
7. The class of entities defined in this Ruling may rely on its contents provided the scheme actually carried out is carried out in accordance with the scheme described in paragraphs 18 to 102 of this Ruling.
- •
- for taxable fuel acquired for use in equipment and machinery without telematics and GPS data directly sourced by Directed
- •
- for taxable fuel acquired and used in vehicles less than 4.5 tonnes (light vehicles) gross vehicle mass (GVM) where there is no entitlement to fuel tax credits
- •
- where the sample size is insufficient for vehicles greater than 4.5 tonnes GVM (heavy vehicles)
- •
- if there are software and system updates or changes that will affect the tax outcome of the scheme outlined in paragraphs 18 to 102 of this Ruling
- •
- if governance, assurance processes and checks are not maintained to ensure that:
- –
- any GPS errors or distortions – such as incorrect distance, idling, or other anomalies – are fixed within the required timeframes, and
- –
- the results remain accurate and truly reflect what happened.
9. Prior to lodging a fuel tax return using the results from the FTC Automator, the client will need to ensure the:
- •
- correctness of their claim on their fuel tax return
- •
- results can be supported by factual evidence (such as engine diagnostic reports and other source documentation) of the events that occurred in carrying on their enterprise, and
- •
- results have not been distorted or manipulated.
10. The ATO must be promptly notified of any software and system updates or changes that may impact the tax outcomes of the scheme outlined in paragraphs 18 to 102.
11. If a vehicle is equipped with a GPS and telematics system, data from that system must be used to determine entitlement instead of a percentage calculated from other sources. Where different types of road transport activity are undertaken, a separate representative sample of sufficient size must be analysed to determine the apportionment percentage for each activity. An apportionment percentage determined for one type of road transport activity must not be applied to another type of road transport activity.
12. This Ruling does not address issues arising from system, malware or firmware updates. It also does not apply where such issues remain unresolved, even if mitigation steps were taken and timely notification was provided.
Date of effect
13. This Ruling applies to taxable fuel acquired on or after 1 January 2025 to 31 December 2028 by the class of entities defined in paragraphs 6 and 7 that enter into the scheme for the fuel tax credit results from FTC Automator with source telematics and GPS data from Directed.
14. However, the Ruling only applies to the extent that there is no change in the scheme as described in paragraphs 18 to 102 of this Ruling, or in the entity's involvement in the scheme. If the scheme carried out is materially different from the scheme described at paragraphs 18 to 102 of this Ruling, this Ruling cannot be relied upon and may be withdrawn or modified.
15. Entities who are considering participating in the scheme are advised to confirm with their taxation adviser that changes in the law have not affected this Ruling since it was issued.
Ruling
16. Subject to paragraphs 6 and 7 of this Ruling and the qualifications in paragraphs 11 and 12 of this Ruling:
- •
- Where ongoing fuel tax credit advice from KPMG in relation to GPS data collected from Directed devices is provided, the FTC Automator provides fair and reasonable results for working out the amount of fuel tax credits for the taxable fuel under Division 43 for the class of entities in paragraphs 6 and 7 of this Ruling.
- •
- The methodology applied within the FTC Automator can be used in determining the extent of taxable fuel acquired for use both on and off public roads for the vehicles[2], and auxiliary equipment. The apportionment methodology is fair and reasonable.
- •
- The apportionment methodology assists in determining the fuel tax credits for the taxable fuel to be included in the calculation of the net fuel amount for a tax period under Division 60.
- •
- The FTC Reports containing information on telematics, fuel apportionment, anomalies, verification against source data (where applicable), fuel tax credit calculations and the fuel tax credit for the business activity statement (BAS) that is generated by the FTC Automator for selected tax periods are records (but not the only record) that can be used to support a fuel tax credit claim.
- •
- These reports are in English, retained for 5 years, and are documents that satisfy a record for the purposes of subsection 382-5(8) of Schedule 1 to the Taxation Administration Act 1953 (TAA). Other records relating to fuel acquisition, use of fuel (supporting evidence demonstrating the information from the FTC Automator) and calculations of credits will be required. In addition, other source data records, invoices and environmental criteria documentation will also need to be retained where applicable.
- •
- Provided the scheme ruled on is entered into and carried out as described in this Ruling, the anti-avoidance provisions in Part 4-4 will not apply to an entity referred to in paragraph 6 and 7 of this Ruling.
17. This Ruling is made on the basis of the following necessary assumptions:
- •
- Each of the clients referred to in paragraphs 6 and 7 of this Ruling has acquired or manufactured or imported taxable fuel into the indirect tax zone.
- •
- All parties (including KPMG and clients) will continue to review outcomes and reports generated by the FTC Automator to ensure that they are accurate and reflect events that occurred. Evidence of these reviews will be retained.
- •
- All dealings between any of the class of entities referred to in paragraphs 6 and 7 of this Ruling, Directed and KPMG for the FTC Automator will be at arm's length.
- •
- The scheme will be executed in the manner described in the scheme section of this Ruling and the scheme documentation referred to in paragraph 18 of this Ruling.
Scheme
18. The scheme is identified and described in the following documents:
- •
- formal application for a Ruling received on 19 July 2024
- •
- further information received on 6 September 2024
- •
- documentary evidence, including testing and sampling for governance and assurance controls to support the processes and results, and
- •
- Product Ruling PR 2023/9 FTC Automator platform – use by clients of KPMG and Directed Australia to calculate fuel tax credits.
Note: certain information has been provided on a commercial-in-confidence basis and will not be disclosed or released under Freedom of Information legislation.
19. For the purposes of describing the scheme to which this Ruling applies, there are no other agreements, whether formal or informal, and whether or not legally enforceable, which an entity referred to in paragraphs 6 and 7 of this Ruling, or any associate of such entity will be a party to, which are a part of the scheme.
20. FTC Automator is a telematics technology-based fuel tax credits apportionment, calculation, and reporting platform that is used internally by KPMG to ascertain fuel use for the purposes of calculating fuel tax credits for their clients. It also incorporates validation and anomaly detection processes that are substantially automated. This is complemented with a manual review to ensure the accuracy of the fuel tax credit claim calculation.
21. FTC Automator ingests telematics and GPS data collected from Directed devices that are installed in vehicles. The data is cleansed and validated to facilitate the apportionment of fuel use for the purpose of fuel tax credit calculations.
22. The FTC Automator's way of apportioning fuel is based on the cumulative measurement of fuel actually used in on or off public roads activities relative to the total fuel used. The apportionment methodology does not rely on vehicle activity such as idle time (and the related fuel consumption rate), nor distance travelled and these metrics are not incorporated into any of the fuel tax credit calculations. Where available, these metrics are captured and may be used to help validate the results produced by the methodology.
23. The FTC Automator apportions fuel use between on and off public road activities for vehicles and, where applicable, auxiliary equipment and power take-off (PTO). KPMG classifies roads based on guidance from Fuel Tax Ruling FTR 2008/1 Fuel tax: vehicle's travel on a public road that is incidental to the vehicle's main use and the road user charge, including the use of geotunnels and geofences.
24. The methodology applied by FTC Automator includes the following:
- •
- For heavy vehicles, fuel used information is extracted from the vehicle's Controller Area Network (CAN bus) and the location of fuel use is determined using telematics and GPS data. The proportion of off-road fuel use is calculated by reference to the total fuel used.
- •
- Where a vehicle has PTO or auxiliary equipment, KPMG compares the calculated off-road fuel percentage to any applicable safe harbour percentage in Practical Compliance Guideline PCG 2016/11 Fuel tax credits – apportioning taxable fuel used in a heavy vehicle with auxiliary equipment, and applies whichever percentage is higher.
- •
- For light vehicles with telematics and GPS data, the proportion of off-road fuel used is calculated by reference to the total fuel used. The proportion of fuel used for on-road activities is excluded from fuel tax credits calculation.
25. The FTC Automator calculates the result using the:
- •
- data upload from telematics, vehicle or asset registers and fuel records
- •
- data validation and quality assessment
- •
- road classification
- •
- distance calculation (for display purposes only)
- •
- fuel use calculation
- •
- fuel tax credit calculation, including anomaly resolution and recalculations
- •
- client consultation or explanation and final advice for submission.
26. KPMG and Directed implement a 2-step data assurance and validation process:
- •
- Firstly by Directed, which includes data capture, processing, validation and storage through Directed's Ethings data management system, and includes the following
- –
- the data must comply with the SAE J1939 CAN bus and FMS vehicle messaging standard
- –
- geocoding and map matching – identify the address for each data point received to confirm it can be found
- –
- data validation – data is validated to ensure that GNSS location records are timestamped, that timestamps are plausible, and that recorded speeds are plausible
- –
- vehicle validation – collected data is validated to confirm that it originates from the correct vehicle and represents valid vehicle data
- –
- data identified as invalid is flagged for investigation and does not get used until it has been verified
- –
- data is managed in accordance with the Australian Privacy Principles and secured in accordance with relevant laws.
- •
- Secondly by KPMG, which includes applying safeguard rules[3], automated reconciliation and, where necessary, resolution of the following
- –
- vehicle details in telematics and GPS data against the client's asset register
- –
- fuel use to fuel acquisition reconciliation, supplemented by manual sample checks
- –
- assessment of road classification in relation to on and off public roads
- –
- in-situ map visualisation of vehicle trips and hot spot detection to identify frequently visited locations
- –
- evidence-based methodology (fuel records, odometer readings, job sheets, diagnostic reports, and sampling of routes) to check for accuracy
- –
- additional exceptions capability to identify anomalies requiring resolution
- –
- FTC Report that includes a cover page, FTC summary for BAS, FTC calculation summary, FTC calculation details, a telematics data report (titled 'Fuel app't rpt-telematics'), vehicle daily activity telematics report, Anomaly Report, verification reports, and vehicle in-scope analysis
- –
- transparent and full explanation to clients about the claim preparation methodology and resulting calculation.
Hardware
27. Directed collects data from the vehicle and associated sensors through telematics devices. The devices are the same as those installed in vehicles by heavy vehicles manufacturers, for government authorities and enterprise customers.
28. There are 2 types of installation:
- •
- the original equipment manufacturer (OEM) installation for manufacturers of certain vehicles, and
- •
- standard installation – installation of the DTU by either Directed or the client.
29. The DTU is vehicle-specific, the installation procedure is consistent across vehicle types, and by a qualified installer.
30. Once installed, the DTU installation is verified through software to confirm that the device is installed correctly and communicating with the Ethings data management system.
31. Directed's processing, governance and validation controls ensure the quality of data collected. Where a device is incorrectly installed or faulty, Directed's data processing and validation processes identify the issue for resolution.
Configuration, records, data upload and validation
32. Directed's telematics data is made available to KPMG through a secure comma-separated values (CSV) file transfer. KPMG will process the data, including applying safeguard rules, upload this data, as well as associated client supplied information such as fuel records, vehicle and asset registers, and any other relevant data to FTC Automator. If a vehicle record is missing mandatory data fields, it will be discarded unless it meets the minimum data requirements, in which case it will proceed to the next stage of processing. The data upload frequency depends on the terms and conditions of the KPMG engagement.
33. The fields[4] for the template to upload to the FTC Automator are:
- •
- telematics identification number (ID)
- •
- asset number
- •
- vehicle or asset registration number
- •
- vehicle make
- •
- model
- •
- vehicle type
- •
- auxiliary equipment
- •
- trip ID
- •
- date from (GPS time)
- •
- date to (GPS time)
- •
- date from (local time)
- •
- date to (local time)
- •
- latitude
- •
- longitude
- •
- Pdop
- •
- Hdop
- •
- heading
- •
- direction
- •
- odometer or vehicle distance (metres)
- •
- engine status
- •
- ignition status
- •
- auxiliary or PTO on or off
- •
- PTO fuel (millilitres)
- •
- vehicle speed (kilometres per hour)
- •
- engine speed (RPM)
- •
- total fuel or fuel usage (millilitres)
- •
- fuel flow rate or fuel use rate (millilitres per hour)
- •
- fuel level or refuel flag
- •
- Combination Weight (kilograms).
Records
34. The client provides fuel records and vehicle and asset register relating to the claim periods. Other relevant documents are provided as relevant (for example, Deed of data release, sample job sheet).
35. The relevant information from the fuel records and the vehicle and asset register is uploaded to FTC Automator. Depending on the specific record, this may include details such as the Telematics ID, asset number, transaction data (date, fuel type, litres, location and odometer reading), and vehicle information (make, model, type and configuration).
36. Other records used for the client file or used for verification of time and location accuracy against the telematics data are obtained as relevant.
Validation
37. During upload, the data is subject to a range of cleansing, validation, and quality checks to ensure that the data quality is acceptable for further processing and an accurate fuel tax credits calculation. KPMG will be alerted to vehicles with erroneous data which will need to be reviewed or removed from the sample size. The 'cleaner' data will be then uploaded again for further processing.
38. The validation rules and other quality checks undertaken during this stage include (but are not limited to):
- •
- checking for duplicate details such as asset identification, vehicle registration, date and time stamp, latitude and longitude and vehicle speed
- •
- checking that fuel records are free of errors, confirming odometer information and vehicle's telematics data details
- •
- removing fields with empty values or device default values that do not impact fuel use measurement or the distance calculation.
39. Once uploaded, further validation checks are performed by the FTC Automator, and the results are provided in the FTC Report where available. These results are reviewed and supplemented through manual verification. Validation activities include, but not limited to:
- •
- reconciliation of telematics fuel used against fuel purchases
- •
- verification of the accuracy of locations recorded in the telematics data
- •
- verification of the accuracy of distances recorded in the telematics data
- •
- verification of the accuracy of road classifications.
Transmission information and data collection
40. The DTU is connected to the vehicle's CAN bus, with integration undertaken with cooperation from the vehicle manufacturer.
41. The DTU collects data from the telematics device, sourced either from the vehicle via the CAN bus or sensors. CAN-bus-derived vehicle data includes odometer readings, speed, fuel information, PTO activity, events, and aggregated trip data. Sensor-derived data includes GNSS location, GPS speed, virtual GNSS-based odometer readings, and gyroscopic data.
42. Data is transmitted in near real time except for where there are communication coverage issues. When coverage is unavailable, the telematics unit stores the data until communications are restored, generally between 2 weeks to one month. It is then transmitted to ensure all data is available in the Ethings platform.
43. Data is collected at intervals ranging from second by second to several minutes. The DTU formats data into DTU messages which are transmitted securely to Ethings using a Directed message format.
44. Ethings receives and stores the DTU messages, performs formatting, checks and validations and then makes the data available in the prescribed format for KPMG. The parameters (which may vary by fleet in some instances) include speed, heading, distance, location, ignition on or off, and moving from stationary.
45. The parameters can be adjusted and tailored to an OEM's needs; any changes will need to be discussed with the OEM. As part of the process, Directed detects and resolves misconfiguration issues, including maintaining audit trails to identify vehicle settings, recording changes made, monitoring anomalies, and supporting the rectification process.
46. When odometer and fuel readings come directly from the vehicle rather than being derived, they match the values shown on the dashboard. These readings align with the physical odometer and fuel levels and are updated with each message sent by the telematics unit.
47. The odometer, speed, and distances data displayed in FTC Automator is sourced from the vehicle's CAN bus data by default. If this is unavailable, the system flags this in the 'Anomaly Report' to indicate that the vehicle is using GPS-based distance instead. This may occur for a specific vehicle where an odometer in a vehicle is faulty from GNSS data. This enables KPMG to process the data and display distances. This can also apply to a fleet of vehicles where they are only able to provide odometer readings via GPS due to the nature of the vehicles. The GPS-based odometer is the use of time and position to calculate the distance travelled and update the odometer values rather than the odometer taken directly from the CAN bus.
48. The data collected can vary depending on the make and the model and requires some harmonisation among manufacturers.
49. Once data is ingested, Directed processes and prepares the data for storage using a standardised data scheme structure. The converted data is in a format that can be transferred between platform services and storage services. Data is also validated to ensure consistency.
50. In the event of a disaster, Directed operates an infrastructure-as-code approach. This means Directed can recover systems using their code tools to ensure system recovery.
51. Data captured cannot be manipulated and is tamper-proof. The data is secured in accordance with the relevant laws.[5]
52. Directed store data in a primary cloud-based storage service. Data retention can vary for each client and is based on commercial agreements. Typically, data is retained for at least 12 months but in many cases, it can be retained for longer.
Road map data and geofences
53. OpenStreetMap is used in FTC Automator for the road data, and then overlaid with for road classification[6], geotunnels and geofencing.
54. As the status of some roads may change over time there are controls and governance processes in place to review details to ensure they are correct. These are undertaken prior to preparing a fuel tax credit claim to ensure the fuel tax credit entitlements are determined correctly.
55. The geotunnel parameter is set at 30 metres from the middle line on either side of a lane a public road. This is applied to all public road map layer data in the OSM shapefiles within Australia. All GPS points within the geotunnel parameter are classified as on public roads, while data points outside the geotunnel are classified as off public road, subject to the geofence rules.
56. In FTC Automator a geofence is used to 'fence' off an area that is not considered a public road. There are KPMG geofences and KPMG-client-level geofences. Certain geofences have a limited timeframe. Geofence boundaries are locked. Any changes to the geofence are logged in an audit trail. If an error in the geofence boundary is identified subsequent to a fuel tax credit claim already lodged, a recalculation will occur, and an adjustment or correction made accordingly.
57. KPMG sets relevant geofences based on a combination of geotunnel boundaries, satellite images and land parcel information based on guidance in FTR 2008/1. If necessary, KPMG will work with the client to set geofences applicable to their business.
58. As all claims are calculated by KPMG in the FTC Automator, KPMG user will review the locational data prior to consulting with the client. This includes reviews for any map anomalies. Where map anomalies are identified, they are rectified and approved by the Tax Lead Adviser. The amount of fuel tax credit is then recalculated.
59. FTC Automator has a visualisation function (including hotspot analysis) where trips will appear for the entire fleet by default. Specific selections such as vehicle, location, hot spots, or other parameters can be viewed for a trip or routes of the fleet. This function enables KPMG to identify locations that may be incorrectly classified or require classification.
Distance calculation for display
60. FTC Automator calculates travel distance by using odometer readings from each GPS ping. For every ping, it subtracts the previous reading from the current one to determine the distance travelled. These distances are classified into on-road and off-road travel and then summed accordingly for the entire period.
61. A Total daily odometer distance is derived and is used to determine whether off public road distance and fuel use is reasonable. This is a way to identify potential anomalies and can easily be mapped to a driver's job sheet or fuel records where odometer readings are available. The distance calculation takes the approach that the transitioning distance, from the last 'ping' reading in an off the public road location to the public road and vice versa, is always classified as the distance travelled on the public road. This parameter (distance) may be used in some circumstances to apportion fuel use.
Apportionment methodology
Heavy vehicles
62. For a client with telematics data for every heavy vehicle (telematics coverage of 100%) and for all tax periods, the apportionment of fuel use is as follows:
- •
- Determine the quantity of fuel use as extracted from the CAN bus data in millilitres in a period.
- •
- Determine where the use took place based on the location of the GNSS coordinates.
- •
- Classify whether the fuel use was on or off public roads (guided by FTR 2008/1 and the application of geotunnels and geofences).
- •
- The off public road fuel is divided by the total fuel to arrive at an off-road fuel use percentage for the period (FTC Automator percentage).
- •
- If a vehicle has auxiliary equipment or PTO, this off-road fuel use percentage is compared to the ATO accepted percentages[7], the higher of the 2 will be used in apportioning fuel use. If the ATO-accepted percentage is to be applied, it will be excluded from any weighted average calculation. The FTC Automator percentage can only be applied with appropriate substantiation.
63. The fuel tax credit calculation is:
- •
- total fuel tax credits = (on-road fuel tax credit rate × total fuel used on public road) + (all other business use (off-road) rate × total fuel used off public road)
- •
- total fuel acquired for all heavy vehicles = invoiced fuel
- •
- total fuel used off public road = invoiced fuel × FTC Automator percentage
- •
- total fuel used on public road[8] = invoiced fuel[9] − total fuel used off public road
64. The total fuel used as processed in FTC Automator is reconciled with the total fuel acquired or used based on a client's fuel statements or invoices.
Light vehicles
65. The basis of the fuel tax credits calculation for light vehicles is:
total fuel tax credits for light vehicles with telematics data = (0 rate × total fuel used on public road) + (all other business use (off-road) rate × total fuel used off-public road)
Where:
- •
- total fuel acquired for each light vehicle with telematics data = Invoiced fuel for each of the light vehicles
- •
- total fuel used off-public road = invoiced fuel × FTC Automator %
- •
- total fuel used on public road = invoiced fuel − total fuel used off-public road
Note: fuel used by light vehicles with no telematics data is ignored for the calculation for fuel tax credits.
66. FTC Automator percentage for fuel used in light vehicles is not used to determine any other apportionment percentages such as fleet-wide average off-road fuel used.
Clients with telematics data and distance data for some heavy vehicles, but not their entire fleet
67. For a client with telematics data for less than the entire fleet of heavy vehicles (telematics coverage of less than 100%), the apportionment of fuel use depends on whether the method is appropriate to the business operation. The 3 methods that can be used are:
- •
- sample size-based – the Australian Bureau of Statistics Sample Size Calculator[10] is used to determine if the telematics coverage is acceptable for fleets with similar trucks
- •
- cost centre-based – where a cost centre may perform unique activity, and
- •
- activity-based – such as long haul, short haul, mining.
Sample size-based apportionment – heavy vehicles only
68. The fuel tax credit calculation for a sample-sized based apportionment is:
total fuel tax credits = (on public road fuel tax credit rate × total fuel used on public road) + (all other business use (off-road) rate × total fuel used off public road)
69. To determine 'total fuel used off public road' and 'total fuel used on public road' for sample size-based apportionment, the following will apply:
- •
- A weighted FTC Automator percentage for the fleet is determined by dividing 'total off public road fuel use in vehicles quantified by telematics' by 'total fuel use in vehicles quantified by telematics'.[11]
- •
- This weighted FTC Automator percentage is then applied to the fuel acquired for each of the heavy vehicles with no telematics coverage.
- •
- For vehicles with telematics coverage, the vehicle's FTC Automator percentage will be used to apply to the fuel acquired for the vehicle.
- •
- For vehicles with auxiliary equipment (as per asset register) but no telematics coverage, the higher of the ATO-accepted safe harbour percentage and the FTC Automator fleet-wide percentage will be used where relevant.
- •
- For vehicles with auxiliary equipment (as per the asset register) and telematics coverage, the higher of the Commissioner's accepted percentage and the vehicle's Automator percentage is used where relevant.
- •
- If the ATO accepted percentage is applied, it will be excluded from any weighted average calculation.
Cost centre-based and activity-based apportionment – heavy vehicles only
70. The fuel tax credit calculation for cost centre-based and activity-based apportionment is:
total fuel tax credits = (on public road fuel tax credit rate × total fuel used on public road) + (all other business use (off-road) rate × total fuel used off public road)
71. A broad extrapolation from a sample of vehicles may not be appropriate as it could skew the off-road fuel use percentages. When a client's business operation requires the cost centre and activity-based approach, applying the following will determine the 'total fuel used off public road' and 'total fuel used on public road':
- •
- Vehicles are categorised into their cost centre or activity group.
- •
- Applying a similar concept as in the sample size-based approach in paragraphs 68 and 69 of this Ruling, a weighted FTC Automator percentage for the vehicles in the relevant cost centre or activity group is obtained by dividing 'total off public road fuel use in vehicles quantified by telematics' by 'total fuel use in vehicles quantified by telematics'.
- •
- This weighted FTC Automator percentage is then applied to the fuel acquired for each of the vehicles with no telematics coverage within the relevant cost centre or activity group.
- •
- For vehicles within the cost centre or activity group with telematics coverage, the vehicle's FTC Automator percentage will be used to apply to the fuel acquired for the vehicle.
- •
- For vehicles with auxiliary equipment (as per the asset register) and telematics coverage, the higher of the ATO's accepted percentage[12] and the FTC Automator percentage is used where relevant.
- •
- For vehicles with auxiliary equipment (as per the asset register) but no telematics coverage, the higher of the ATO accepted percentage[13] and the FTC Automator (fleet-wide, cost centre based) percentage will be used where permissible.
Fuel use apportionment and calculation – heavy vehicles
72. Where appropriate for heavy vehicles with the listed auxiliary equipment, the ATO accepted percentages outlined in PCG 2016/11 will be used. When these percentages are applied, they will not be used in conjunction with another methodology.[14]
73. The CAN bus data is also relied upon to report fuel use once it has been verified as acceptable against fuel records. The amount of fuel used in a period is determined by subtracting an earlier total fuel or fuel usage (millilitres) from a later total fuel or fuel usage (millilitres).
74. For vehicles with CAN bus fuel data, the apportionment of fuel use is based on quantity of fuel used and disregards the vehicle activity (driving, idling and time). The apportionment is:
- •
- off the public road – attracting the full fuel tax credit rate
- •
- on the public road – reduced fuel tax credit rate (rate reduced by the road user charge) for heavy vehicles
- •
- transitioning fuel use, that is, the fuel use when a vehicle is crossing from a public road to an off public road or from the last 'ping' reading in an off the public road location to the public road and vice versa. This is classified as fuel used on public roads and the reduced fuel tax credit rate applies for heavy vehicles.
Idle fuel use and idle time
75. Where available, idle fuel use and idle time are used to derive the idle fuel consumption rate which is intended for display only and not used in any fuel tax credit calculations.
76. The fuel used-idling information may also be used to detect potential data quality issues.
77. If idle fuel and idle time data shows anomalies, data will be reviewed and if warranted, supporting documentation will also be reviewed to verify data integrity. Any errors will be corrected to ensure data integrity across the product.
Governance, assurance, and internal controls
78. To support the Ruling, examples of high quality, high resolution GPS data, governance, assurance and internal controls, reports and the fuel tax credit results were provided.
79. The FTC Automator has built-in and automated governance and assurance processes. It encompasses safeguard rules which are applied prior to data upload, and also requires user intervention to review and rectify any exceptions prior to proceeding to the next step.
80. Controls and governance are in place to ensure:
- •
- data capture is accurate, secure and tamper-proof
- •
- the device is vehicle specific
- •
- telecommunications or transmission coverage are not limited or interrupted
- •
- representativeness of the sample
- •
- appropriate data storage and backup
- •
- data accuracy
- •
- reliability of road map data and road classification
- •
- appropriate system updates and maintenance
- •
- accuracy of system outputs
- •
- data security
- •
- fuel tax credit rates – ensuring that the rates used are the rate in force and compared to the rates on www.data.gov.au
- •
- correct use of the FTC Automator.
81. Other governance undertaken includes:
- •
- validation processes to ensure that distances (either GPS or odometer) broadly align with the actual distance travelled by the vehicle
- •
- visualising routes to identify and rectify anomalies by amending the source data classification to ensure there is no misclassification of roads
- •
- fuel used in a sample period broadly aligns with fuel acquired per the fuel records
- •
- anomaly resolution to address and rectify anomalies and gather further evidence as required
- •
- distance verification for the distance travelled on and off public roads. A daily average distance is derived to ensure reasonableness of distance travelled by a vehicle and determine the off public road percentage of distance and fuel use. This process is used to identify potential anomalies. It can extend to mapping to a driver's job sheet or fuel records.
82. As part of ongoing governance to address and resolve any potential anomalies, KPMG reviews a sample of output showing in the Anomaly Report (including the apportionment percentages for each of the vehicles) and either resolves the potential anomaly or accepts it where there is an acceptable explanation based on the evidence available. KPMG verifies any records that support the claim. For example, if the off public road fuel use is considered to be higher than expected, KPMG will verify the routes and fuel use of the vehicle via the fuel records, job sheets, geofence areas, or delivery records to support or, modify the percentages. If an anomaly is not identified, KPMG will still continue review and check some samples against business records to ensure accuracy.
83. The documentary evidence provided for this Ruling assurance process includes the following (but not limited to):
- •
- in-vehicle testing (trials and actual testing) pertaining to a variety of travel conditions and terrain (highway, country, dense urban, low speeds, dry and wet conditions, hills, various speeds, public roads)
- •
- activities off public roads. This testing involved reality check processes and distance verification, driving fuel consumption verification. The testing included analysing the data against the test drive notes and independent telematics data collected during the drive test. The results were verified. The purpose was to ensure and obtain evidence that the factual activity of the vehicle aligned with the data story
- •
- data accuracy information – verification of the data with mapping sources, engine management systems, and reports, and
- •
- road classification and evidence to support apportionment between public roads and other uses.
Fuel tax credit calculation and reporting
84. The apportionment is a cumulative measurement of fuel and whether that fuel was used on or off a public road.
85. Supplementary steps are taken to verify the accuracy of fuel used and distance travelled.
86. Validation rules are always applied to the data received and KPMG reviews all data, including addressing exceptions and resolving any potential anomalies showing in the 'Anomaly report'. KPMG gathers further evidence if warranted. Once the anomalies and exceptions are resolved, FTC Automator processes the data and calculates the amount of fuel tax credit entitlement in a report generated along with a summary in the user interface. The calculation is:
- •
- heavy vehicles for travelling on public roads – reduced fuel tax credit rate (taking account of the road user charge)
- •
- all other business fuel uses including fuel used off public roads – full fuel tax credit rate.
87. The fuel tax credit rates reference table is based on the fuel tax credit rates published on the ATO website and historical rates on www.data.gov.au.
88. The fuel tax credits calculation is supported by relevant evidence which may contain further documentation from the client. This aims to clarify and address the reason for any anomalies which are to be accepted or resolved (where applicable).
89. A final fuel tax credits calculation is created in the FTC Report and printed out electronically in portable document format (PDF) or Microsoft Excel format for review and discussed with the client. The PDF or Microsoft Excel file may be locked to prevent it from being edited. If any changes are required, KPMG make the changes in the FTC Automator and share the final calculation with the client in an updated PDF or Microsoft Excel report along with FTC Workpaper, and a letter of advice.
90. Only after a discussion explaining all relevant details with the client can a fuel tax credit claim be lodged. This is to ensure that the client understands and agrees with the calculation prior to any fuel tax credit claim being included on a BAS that is lodged with us. The lodgment of the fuel tax credit claim can be made by KPMG on behalf of the client, or by the client as governed by the terms and conditions of the client engagement.
91. The FTC Report that is compiled by FTC Automator and provided to clients. contains multiple sections, comprising of:
- •
- cover page
- •
- FTC summary for BAS
- •
- FTC calculation summary
- •
- FTC calculation detailed
- •
- a telematics data report (fuel apportionment report – telematics)
- •
- vehicle daily activity telematics report
- •
- anomaly report
- •
- verification reports (fuel distance location and transaction)
- •
- vehicle in-scope analysis.
92. The FTC Report enables KPMG to check the details, as it can be aligned with driver job sheets or fuel records for any given day. All these reports are provided to the client for discussion prior to submitting a claim.
93. The Telematics information shows the hot spots analysis where routes of the vehicles can be visualised with filters to shortlist vehicles and dates for the in-situ analysis.
94. The anomaly report outlines potential anomalies in the data for the vehicle and auxiliary equipment. It identifies the date and the location of the anomaly and contains relevant fields to input whether the error has been resolved and the basis for the decision reached. It includes information such as:
- •
- anomaly test exception case
- •
- vehicle or Asset ID
- •
- date
- •
- vehicle type or configuration
- •
- auxiliary equipment
- •
- GVM (tonnes)
- •
- vehicle weight class
- •
- apportionment period start date
- •
- apportionment period end date
- •
- business unit
- •
- use activity type (for example, forestry, farm or long haul)
- •
- fuel type
- •
- total invoice fuel (litres)
- •
- FTC Automator Fuel (litres)
- •
- FTC Automator Apportionment percentage (including auxiliary or PTO)
- •
- accept (yes, no or rectified)
- •
- reason.
95. The Fuel Apportionment Report generated by FTC Automator shows the apportionment percentages, litres allocated for the various uses on and off public roads for the vehicle and auxiliary equipment as following:
- •
- vehicle or asset ID
- •
- vehicle type or configuration
- •
- auxiliary equipment
- •
- GVM (tonnes)
- •
- vehicle weight class
- •
- ATO safe harbour percentage
- •
- apportionment period start date
- •
- apportionment period end date
- •
- business unit
- •
- use activity type (forestry, farm, long haul)
- •
- main use
- •
- location type
- •
- invoice fuel within telematics period (litres)
- •
- odometer distance for the sample period (kilometres)
- •
- total engine on time (hours)
- •
- public road distance (kilometres)
- •
- driving time on public road (hour)
- •
- idling time on public road (minutes)
- •
- driving fuel use on public road (litres)
- •
- idling fuel used on public road (litres)
- •
- off public road distance (kilometres)
- •
- driving time off public road (hour)
- •
- idling time off public road (minutes)
- •
- driving fuel used off public road (litres)
- •
- idling fuel used off public road (litres)
- •
- fuel used in geofence (litres)
- •
- auxiliary or PTO fuel (litres)
- •
- total fuel used (litres)
- •
- public road fuel used (percentage)
- •
- FTC Automator apportionment percentage (including auxiliary or PTO)
- •
- auxiliary or PTO fuel percentage
- •
- fuel rate driving on public road (litres per 100 kilometres)
- •
- fuel rate driving off public road (litres per 100 kilometres)
- •
- fuel rate idling on public road (litres per hour)
- •
- fuel rate idling off public road (litres per hour)
- •
- fuel rate off public (litres per hour)
- •
- fuel rate (litres per kilometre) overall.
96. The FTC calculation tab not only shows the percentages allocated on and off public roads but provides the amount in dollars of fuel tax credits allocated to the full rate or the rate for heavy vehicles for travelling on public roads.
97. An FTC Workpaper is also provided for the apportionment methodology used for all clients.
98. The FTC Workpaper contains multiple sections, comprising of:
- •
- claim
- •
- FTC rates
- •
- historical claims
- •
- fuel and apportionment
- •
- fuel usage workpaper
- •
- apportionment rates.
Record keeping
99. With the client's consent, all data and records, including Directed telematics data, relating to the fuel tax credit calculation is stored for at least 5 years in the KPMG system. KPMG becomes the holder of that same data. All of this information is in English.
100. All data and records relating to the fuel tax credit calculations will be stored by Directed for at least one year.
101. Data is archived and replicated to prevent any data loss during a disaster or any down period at a data centre.
102. Clients receive a fuel tax credits report and are advised to retain in their own records for at least 5 years.
Commissioner of Taxation
14 October 2026
Appendix – Explanation
|
This Explanation is provided as information to help you understand how the Commissioner's view has been reached. It does not form part of the binding public ruling.
|
| Table of Contents | Paragraph |
| Use of the FTC Automator for fuel tax credit purposes | 103 |
| Whether apportionment is a requirement to work out the entitlement to a fuel tax credit | 103 |
| Principles for apportioning fuel used in a vehicle | 108 |
| Whether the FTC Automator provides a step in the apportionment of fuel | 116 |
| Whether the apportionment methodology is fair and reasonable | 130 |
| Whether the FTC Automator generates fair and reasonable results for working out the amount of fuel tax credits as per Division 43 of the Fuel Tax Act 2006 | 143 |
| Whether the amount of fuel tax credits worked out by the FTC Automator can be used in working out the net fuel amount for a tax period | 146 |
| Whether the FTC output template (named the FTC report) can be used for record-keeping purposes (but not the only record) | 150 |
| Summary | 162 |
| Part 4-4 – anti-avoidance | 165 |
Use of the FTC Automator for fuel tax credit purposes
Whether apportionment is a requirement to work out the entitlement to a fuel tax credit
103. An entity is entitled to a fuel tax credit for taxable fuel (referred to as fuel) that it acquires or manufactures in, or imports into, the indirect tax zone to the extent that the entity does do so for use in carrying on the entity's enterprise. However, to be entitled to a fuel tax credit in respect of the fuel, the entity must be registered or required to be registered for goods and services tax at the time the entity acquires, manufactures, or imports the fuel (subsections 41-5(1) and (2)).
104. Section 41-20 confirms that there is no entitlement to a fuel tax credit for fuel to the extent that an entity acquires, manufactures, or imports the fuel for use in a light vehicle travelling on a public road.
105. Division 43 sets out how to work out the amount of a fuel tax credit. Fuel tax credits for fuel acquired for use in heavy vehicles are reduced by the road user charge to the extent that the fuel is for travelling on a public road under subsection 43-10(3).
106. The use of the phrase 'to the extent' in sections 41-5, 41-20 and subsection 43-10(3) contemplates apportionment between fuel acquired for an eligible use and fuel acquired for an ineligible use or uses which may give rise to different rates of fuel tax credit entitlement.
107. To determine the entitlement and the amount of fuel tax credit, an entity that acquires fuel for use in vehicles will need to apportion the fuel between:
- •
- vehicles with a GVM exceeding 4.5 tonnes
- –
- the extent to which the fuel is for use in a vehicle for travelling on a public road (where the fuel tax credit rate is the excise duty rate less the road user charge)
- –
- the extent to which the fuel is for other uses (where the fuel tax credit rate is the excise duty rate)
- •
- vehicles with a GVM of 4.5 tonnes or less
- –
- the extent to which the fuel is for use in a vehicle travelling on a public road
- –
- the extent to which the fuel is acquired other than for use in a vehicle travelling on a public road, and
- •
- other circumstances in which there is no entitlement including use in heavy diesel vehicles that do not meet the environmental requirements or where another entity has entitlement to a fuel tax credit in respect of the fuel.
Principles for apportioning fuel used in a vehicle
108. The Fuel Tax Act 2006 contemplates apportionment but does not prescribe any set method for apportioning fuel between different uses. The Commissioner explained in Fuel Tax Determination FTD 2010/1 Fuel tax: apportionment may apply when determining total fuel tax credits in calculating the net fuel amount under section 60-5 of the Fuel Tax Act 2006 that fuel tax credit entities can use any apportionment method that is fair and reasonable to their circumstances.
109. Paragraph 33 of FTD 2010/1 states:
It is not necessary for an apportionment method to track the intended use of every last drop of fuel. A method may be fair and reasonable without doing so provided that the application of the method reasonably reflects the extent to which taxable fuel is acquired for an eligible activity.
110. Apportionment of fuel for the purpose of working out an entitlement and calculating the amount of the entitlement are distinct phases. An entity can generally perform separate calculations where there are one or more types of fuel for use in the same or multiple activities. A single calculation may be performed for example, where there is the same type of equipment that uses different types of liquid fuel and at the same fuel consumption rate for both types of fuel.
111. The amount of the entitlement calculated should be the same whether a single step process or a discrete step calculation is performed. The apportionment should not result in more fuel being taken into account than has been acquired, manufactured or imported or used and that the apportionment of fuel is reasonable (for example, fuel used in a heavy vehicle for travelling on public roads is reasonable compared to fuel used off public roads for loading, unloading, or idling purposes).
112. To apportion the fuel an entity has acquired to the different activities for which the fuel was used, a reliable measure can be used as part of an apportionment methodology for calculating the amount of fuel that is acquired for use in an eligible activity.
113. Examples of known reliable measures include:
- •
- odometer readings of kilometres actually travelled
- •
- route distances
- •
- hours of operation of equipment
- •
- engine monitoring systems
- •
- fuel consumption trails on the vehicles or equipment used in the entity's business under similar operating conditions, and
- •
- telematics technology that produces accurate results and where it supports actual events, data is captured accurately, roads and areas have been correctly classified and geofenced and, that the results are not distorted and can be supported by source documentation.
114. Although these are commonly used measures, because of the diverse range of eligible activities, paragraph 113 of this Ruling is not an exhaustive list and there may be other measures that are appropriate to an entity's circumstances. There also needs to be assurances in place to ensure that any measure used does not distort results.
115. The FTC Automator is a telematics technology product that can be used as a measure in the apportionment process as it has functionalities for data to be transmitted and events to be categorised on use. It will be a reliable measure provided that:
- •
- GPS data is accurate
- •
- any software, system and firmware updates affecting the tax outcome are addressed
- •
- governance, assurances and controls in place are maintained
- •
- any errors are corrected in a timely manner, and
- •
- the checks are undertaken to ensure that the results generated continue to be accurate and are not distorted.
Whether the FTC Automator provides a step in the apportionment of fuel
116. There are 2 types of installation of the DTU that is used to collect data before it is transmitted to FTC Automator. The installation is either by the vehicle manufacturer or, by Directed. Data is transmitted, formatted, and analysed. The client provides fuel records and vehicle or asset registers relating to the tax period applicable to the relevant data.
117. The reporting of fuel readings is from the vehicle itself via CAN bus, it is not derived or implied. These readings are consistent with that displayed to the driver on the dashboard. Also, fuel invoices for the tax period are supplied to KPMG to support fuel use and for the relevant apportionment of fuel.
118. KPMG applies validation rules and analyses the data received.
119. For heavy vehicles, fuel use is apportioned depending on whether the client's fleet has full or partial telematics coverage, or whether another method better suits the business operation, such as a cost-centre or activity-based approach.
120. The steps involved in the apportionment methodology include determining:
- •
- the quantity of fuel use based on engine diagnostic data (if applicable), and
- •
- where that fuel use occurred.
121. The percentage of fuel used off public roads is determined and then deducted from the total invoice fuel for the tax period to apportion to fuel used on public roads.
122. The total fuel tax credits are then calculated. Any exceptions or anomalies identified during the process are addressed, after which a final fuel tax credit calculation is completed.
123. If not all the heavy vehicles in the fleet have telematics devices, a sample size is used based on the Australian Bureau of Statistics Sample Size Calculator to determine if the telematics coverage is acceptable. Similar to the steps outlined in paragraph 120 of this Ruling, a weighted FTC Automator percentage is determined and the steps involved in the apportionment methodology are outlined in paragraphs 68 and 69 of this Ruling.
124. Where the methodology is based on cost centre or activity approach, the vehicles are categorised into the cost centre or activity group. Applying a similar approach as above, a weighted FTC Automator percentage is applied by dividing 'total off public road fuel use in vehicles quantified by telematics' by 'total fuel use in vehicles quantified by telematics' within those groups. This percentage is then applied to the fuel acquired for each of the vehicles with no telematics coverage within the cost centre or activity group.
125. For vehicles with auxiliary equipment (as per asset register) but no telematics coverage, the higher of the ATO-accepted safe harbour percentage and the FTC Automator fleet-wide percentage will be used where relevant.
126. For vehicles with auxiliary equipment (as per the asset register) and telematics coverage, the higher of the Commissioner's accepted percentage and the vehicle's FTC Automator percentage is used where relevant.
127. If the ATO accepted percentage is applied, it will be excluded from any weighted average calculation.
128. For light vehicles with telematics and GPS data sourced by Directed, the apportionment methodology steps involve include determining the quantity of fuel use (invoiced) and that the fuel use occurred off public roads.
129. The use of FTC Automator provides a step in the apportionment of fuel by categorising fuel use.
Whether the apportionment methodology is fair and reasonable
130. Paragraph 2.86 of the Revised Explanatory Memorandum to the Fuel Tax Bill 2006 and the Fuel Tax (Consequential and Transitional Provisions) Bill 2006 explains that an entity needs to apportion fuel use between eligible and ineligible uses in calculating their fuel tax credit entitlement:
If a taxpayer acquires, manufactures, or imports fuel for both eligible and ineligible activities, they will need to apportion the use of that fuel between eligible and ineligible uses to determine the amount of the fuel that is eligible for a fuel tax credit.
131. We consider that where an entity is required to apportion the use of fuel between eligible and ineligible uses or multiple eligible uses, the use of the words 'to the extent that' allows an entity to choose a method of apportionment that is fair and reasonable in the circumstances.
132. The principles to be applied in identifying situations where apportionment is appropriate in an income tax context, and the method to be employed where apportionment is required, were considered in an income tax context by the High Court in Ronpibon Tin NL and Tongkah Compound NL v Federal Commissioner of Taxation [1949] HCA 15 (Ronpibon). The High Court considered what parts of expenses incurred by a taxpayer were referable to gaining or producing assessable income. The High Court considered both the allocation of distinct expenditure to specific activities, and apportionment.
133. Following the principles set out by the High Court in Ronpibon, an entity can use any method to apportion fuel to take into account the requirements of the entitlement and calculation provisions, but that method needs to be fair and reasonable in the circumstances.
134. There may be more than one fair and reasonable basis of apportionment. It follows that the calculation of fuel tax credit entitlements cannot necessarily be carried out with absolute arithmetical precision. Rather, an entity is entitled to a fuel tax credit where the other requirements for entitlement are met and, to the extent that an apportionment is required, the amount arrived at is calculated by application of an apportionment method that is fair and reasonable in the circumstances. It is not necessary for an apportionment method to track the intended use of every last drop of fuel.
135. The apportionment methodology is based on whether the entire fleet has telematics coverage or only partial fleet with coverage. Also, the apportionment of fuel use depends on whether the method is appropriate to the business operation and whether a sample size-based methodology, cost centre-based, or activity-based is considered appropriate.
136. Paragraphs 62 to 74 of this Ruling set out the steps for each apportionment method. The functionality in FTC Automator provides a step in apportioning fuel based on the categorisation of use, that is, fuel used on and off public roads.
137. For vehicles with Directed's DTU, the vehicle's location is recorded based on the satellite data. For most vehicles, the distance travelled is recorded based on engine data, specifically the odometer. This information is used to determine the measure of kilometres travelled (distance) and the location of that travel.
138. The apportionment methodology for heavy vehicles with telematics coverage of the fleet involves determining:
- •
- the quantity of fuel used
- •
- where the fuel was used
- •
- percentage of total fuel used off public roads
- •
- comparison, if applicable, for auxiliary equipment to the accepted percentages outlined in PCG 2016/11
- •
- calculating the amount of fuel tax credits – that is
- –
- total fuel acquired for the heavy vehicle = invoiced fuel
- –
- total fuel used off public road = invoiced fuel × FTC Automator percentage
- –
- total fuel used on public road = invoiced fuel − Total fuel used off public road
- –
- total fuel tax credits = (on-road fuel tax credit rate × total fuel used on public road) + (all other business use (off-road) fuel tax credit rate × total fuel used off public road).
139. Similar steps are undertaken where there is not an entire fleet of heavy vehicles covered by telematics or the method is determined by the business operation. These steps are detailed in paragraph 67.
140. The sampling methodology is applied where the heavy vehicle fleet does not have full telematics coverage. In these circumstances, the sample must be representative of the fleet and of sufficient size to ensure an appropriate level of statistical confidence in the apportionment outcome.
141. The methodology for the vehicle and equipment that is tracked by the satellites along with CAN bus information to be used by FTC Automator is considered a fair and reasonable apportionment of fuel. It is only fair and reasonable where:
- •
- source documentation supports that locational information and engine management usage
- •
- classification of roads is correct, aligned with FTR 2008/1 and up to date
- •
- FTC Automator calculates the fuel used and distance travelled correctly based on the road classification
- •
- FTC Automator determines the quantity of fuel used based on the direct measurement of fuel and calculates fuel consumption rates
- •
- although idle time and idle fuel use is captured, it is not used in the calculation to distort fuel usage or time
- •
- source documentation supports the fuel acquisitions
- •
- a preliminary fuel tax credits calculation is performed
- •
- there is robust governance and controls in place to identify and correct errors including:
- –
- validating the outputs
- –
- reconciling the fuel used and distances to source documents
- –
- reviewed to ensure it has not resulted in apportioning more taxable fuel than the client has acquired
- –
- obtaining further evidence if required
- –
- if any anomalies are identified they are resolved including any software, systems or firmware updates affecting the fuel tax credit calculation
- •
- a final fuel tax credit calculation is performed, and reports are generated
- •
- consultation with the client occurs to explain the fuel tax credit calculation and ensure that there is a correct entitlement to claim fuel tax credits, and
- •
- the reports may be locked to prevent them from being edited.
142. Provided all the points outlined in paragraphs 136 to 141 of this Ruling are reviewed regularly, including checks to ensure data and outcomes remain accurate, the apportionment methodology used by the FTC Automator is fair and reasonable.
Whether the FTC Automator generates fair and reasonable results for working out the amount of fuel tax credits as per Division 43 of the Fuel Tax Act 2006
143. The amount of fuel tax credits is determined with reference to Divisions 41 and 43. The 'fair and reasonable' principle applies in determining the extent of entitlement and the amount of fuel tax credits within these Divisions.
144. FTC Automator applies an apportionment methodology that is fair and reasonable. It incorporates appropriate checks and processes to ensure:
- •
- eligibility to claim fuel tax credits is correctly determined in accordance to Division 41 and Subdivision 41-B[15]
- •
- roads are correctly classified for applying the road user charge to the relevant fuel under subsections 41-10(3) and (4), and
- •
- the amount of fuel tax payable is calculated using the rate in force on the relevant day using the table in subsection 43-5(2A).
145. As a result, FTC Automator provides a fair and reasonable result for working out the amount of fuel tax credit for the class of entities identified in paragraphs 6 and 7 of this Ruling.
Whether the amount of fuel tax credits worked out by the FTC Automator can be used in working out the net fuel amount for a tax period
146. The net fuel amount has the meaning given by section 60-5.
147. In working out the net fuel amount under section 60-5, the following formula applies:
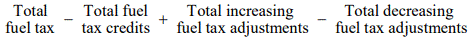
148. The apportionment methodology applied within the FTC Automator to the taxable fuel is fair and reasonable in working out the extent of taxable fuel used both on and off public roads. The results generated in respect of that taxable fuel (for vehicles or equipment) are also fair and reasonable, subject to relevant checks and balances, including governance and assurance processes. The results can be used in working out the amount of fuel tax credits for that taxable fuel within Division 43.
149. As the results generated from the FTC Automator can calculate the amount of fuel tax credits for that taxable fuel, it assists in determining fuel tax credits to be included in the calculation of the net fuel amount for a tax period under Division 60.
Whether the FTC output template (named the FTC report) can be used for record-keeping purposes (but not the only record)
150. Subsection 382-5(1) of Schedule 1 to the TAA provides that you must keep records that record and explain all transactions and other acts you engage in that are relevant to acquisitions (for example, an entitlement to a fuel tax credit).
151. The records must be retained for at least 5 years after the completion of the transactions or acts to which they relate.
152. Subsection 382-5(8) of Schedule 1 to the TAA provides that the records must be in English, or easily translated into English, and enable an entitlement under an indirect tax law, that is, a fuel tax law to be ascertained.
153. All data and records, including Directed telematics data, relating to the fuel tax credit calculations is stored and accessible for at least 5 years.
154. The FTC Report is compiled by FTC Automator and provided to clients. It contains details of the telematics apportionment, data, anomalies and calculations in multiple sections.
155. The tabs within the FTC report show details of telematics information, Anomaly Report, fuel tax credit calculation and summary, the FTC summary for BAS reporting and the fuel apportionment.
156. Depending upon the relevant tab, it may contain vehicle-related information, location information, tax invoice details including litres, distance, apportionment percentage, fuel usage and allocation, anomalies and relevant action and the fuel tax credit calculation.
157. Although the information is contained within relevant Microsoft Excel spreadsheets by KPMG, it enables the client to review the relevant information in conjunction with services provided by KPMG to identify any issues and their correction and, ensure that the data confirms actual events. The report can be used by KPMG and the client to verify the data apportionment calculations and amount of fuel tax credits. The information contained in the reports can be verified with source documentation. The information can then be used for preparing the fuel tax credit claim. The information (data and calculations) and the reports are in English.
158. The template is retained by KPMG for a period of at least 5 years. The report is provided to the client, along with FTC Workpaper, and a letter of advice.
159. The client receiving the FTC Report are advised to retain in their system for 5 years.
160. The FTC Report is a document that is a record for the purposes of subsection 382-5(8) of Schedule 1 to the TAA.
161. However, the FTC Report will not be the only record that is used to determine the apportionment for fuel tax credit purposes or support fuel tax credit claims by a client. Other records may include, but are not limited to, source data input information reports, fuel acquisition records (such as tax invoices), confirmation of location and time (such as driver job sheet) and environmental criteria documentation.
162. FTC Automator processes the GPS data sourced from Directed and applies a set methodology in determining the extent of fuel acquired for use in the nominated vehicles and auxiliary equipment. It can then be used in working out the amount of fuel tax credits for those nominated vehicles and auxiliary equipment under Division 43.
Note: working out the amount of fuel tax credits will require the correct amount of fuel tax that was payable on the fuel at the rate in force on the relevant day using the table in subsection 43-5(2A).
163. The nominated reports (FTC Report) generated from FTC Automator, and the FTC Workpaper, can be used as a record (but not the only record) for the purposes of subsection 382-5(8) of Schedule 1 to the TAA.
164. There are governance and assurance processes that have demonstrated the accuracy and the fair and reasonable results of the FTC Automator. However, checks must continue to be undertaken regularly to ensure that any software or systems issues are rectified and the outcomes reflect actual events, any outliers or errors are corrected, and the results are accurate.
165. Provided that the scheme ruled on is entered into and carried out as disclosed in this Ruling, and that the data, inputs and results generated are not manipulated or tailored to obtain fuel tax benefits by taking advantage of the fuel tax law in circumstances other than those intended by the fuel tax law, Part 4-4, Division 75 will not apply.
© AUSTRALIAN TAXATION OFFICE FOR THE COMMONWEALTH OF AUSTRALIA
You are free to copy, adapt, modify, transmit and distribute this material as you wish (but not in any way that suggests the ATO or the Commonwealth endorses you or any of your services or products).
Footnotes
From Directed Telematics Unit (DTU) device.
Heavy vehicles with and without telematics and GPS data sourced by Directed. Only light vehicles with telematics and GPS data sourced by Directed.
To ensure over apportionment of fuel use to off-road is eliminated.
Not all fields are available for all vehicles, the data must contain at least the minimum mandatory fields.
Data relating to heavy vehicles is maintained and managed as required under the Heavy Vehicle National Law.
Roads are classified according to FTR 2008/1. Public roads are roads that are accessible to the public and integrated into the overall public road network regardless, of whether they are publicly or privately owned, operated, or maintained.
PCG 2016/11.
This may include PTO fuel, however, the client can determine whether to use the ATO accepted percentage from PCG 2016/11 (where applicable) or FTC Automator calculated percentages, subject to availability of evidence. If the ATO accepted percentage from PCG 2016/11 is used, the vehicle is excluded from further apportionment calculations.
All calculations exclude fuel used by light vehicles on the public road and light vehicles with no CAN bus data.
www.abs.gov.au.
Excludes vehicles that use the ATO's accepted percentages outlined in PCG 2016/11.
PCG 2016/11.
PCG 2016/11.
The percentages of taxable fuel that are accepted that the fuel tax credit is not reduced by the road user charge cover both fuel used in powering the auxiliary equipment of the vehicle as well as fuel used while the vehicle is not on a public road.
Entitlement to claim fuel tax credits within Division 41 having regard to disentitlement provisions including sections 41-20 and 41-25.
References
ATO references:
NO 1-1AL6ZV8T
Previous Rulings/Determinations:
TR 2023/9
Related Rulings/Determinations:
FTR 2008/1
FTD 2010/1
Legislative References:
FTA 2006 Div 41
FTA 2006 41-5
FTA 2006 41-5(1)
FTA 2006 41-5(2)
FTA 2006 41-10(3)
FTA 2006 41-10(4)
FTA 2006 Subdiv 41-B
FTA 2006 41-20
FTA 2006 41-25
FTA 2006 Div 43
FTA 2006 43-5(2A)
FTA 2006 43-10(3)
FTA 2006 Div 60
FTA 2006 60-5
FTA 2006 Pt 4-4
FTA 2006 Div 75
TAA 1953 Sch 1 382-5(1)
TAA 1953 Sch 1 382-5(8)
Cases relied on:
Ronpibon Tin NL and Tongkah Compound NL v Federal Commissioner of Taxation
[1949] HCA 15
78 CLR 47
[1949] ALR 785
(1949) 23 ALJ 139
(1949) 8 ATD 431
Other References:
PCG 2016/11
Revised Explanatory Memorandum to the Fuel Tax Bill 2006 and the Fuel Tax (Consequential and Transitional Provision) Bill 2006
Copyright notice
© Australian Taxation Office for the Commonwealth of Australia
You are free to copy, adapt, modify, transmit and distribute material on this website as you wish (but not in any way that suggests the ATO or the Commonwealth endorses you or any of your services or products).
