Draft Taxation Ruling
TR 2026/D3
Total superannuation balance
-
Please note that the PDF version is the authorised version of this draft ruling.For information about the status of this draft Ruling, see item 4181 on our Advice under development program
| Contents | Paragraph |
|---|---|
| What this draft Ruling is about | |
| Ruling | |
| When your total superannuation balance is determined | |
| Determining total superannuation balance | |
| Element 1 – total superannuation balance value | |
| Your superannuation interests | |
| Retirement phase superannuation income streams paid after a member's death | |
| Notional interests | |
| How to determine the total superannuation balance value of a particular interest | |
| Element 2 – roll-over superannuation benefits | |
| Element 3 – LRBA amounts | |
| Element 4 – subtract any structured settlement contributions | |
| Examples | |
| Example 1 – account-based pension and accumulation account | |
| Example 2 – total superannuation balance of death benefit income stream recipient | |
| Example 3 – roll-over superannuation benefit | |
| Example 4 – LRBA amount – condition of release with a nil cashing restriction | |
| Example 5 – LRBA amount – lender is an associate of the superannuation fund | |
| Example 6 – structured settlement contribution | |
| Date of effect | |
| Appendix 1 – Relevance of total superannuation balance | |
| Provisions for which total superannuation balance is relevant | |
| Division 296 tax liability | |
| Eligibility for unused concessional contributions cap carry forward | |
| Non-concessional contributions cap, including bringing forward your non-concessional contributions cap | |
| Eligibility for work test exemption | |
| Eligibility for the government co-contribution | |
| Eligibility for the tax offset for spouse contributions | |
| Small superannuation funds | |
| Appendix 2 – Your comments |
 Relying on this draft Ruling This publication is a draft for public comment. It represents the Commissioner's preliminary view on how a relevant provision could apply. If this draft Ruling applies to you and you rely on it reasonably and in good faith, you will not have to pay any interest or penalties in respect of the matters covered, if this draft Ruling turns out to be incorrect and you underpay your tax as a result. However, you may still have to pay the correct amount of tax. When finalised, this Ruling will be legally binding on the Commissioner, except to the extent that it makes statements regarding the operation of Division 296 of the Income Tax Assessment Act 1997 and associated regulations. |
What this draft Ruling is about
1. This draft Ruling[1] outlines how to calculate your total superannuation balance[2], which is a method for determining the combined value of all your Australian superannuation interests.
2. Your total superannuation balance is relevant for determining your[3]:
- •
- Division 296 tax[4] liability
- •
- eligibility for unused concessional contributions cap carry forward
- •
- non-concessional contributions cap (including the bring forward of your non-concessional contributions cap)
- •
- eligibility for the work test exemption, relevant for deducting personal superannuation contributions
- •
- eligibility for the government co-contribution, and
- •
- eligibility for the tax offset for spouse contributions.
3. Your total superannuation balance is also relevant to any small superannuation funds[5] you are a member of, as it may affect the fund's eligibility to use the segregated assets method when determining its exempt current pension income (ECPI).[6]
4. All further legislative references in this Ruling are to the Income Tax Assessment Act 1997 (ITAA 1997), unless otherwise indicated.
Ruling
When your total superannuation balance is determined
5. The eligibility (or tax liability) for items listed in paragraphs 2 and 3 of this Ruling require the determination of your total superannuation balance at a set time, which is described using varying terminology in different provisions.
6. It is the Commissioner's view that the following terms used in the ITAA 1997 all mean at the end of 30 June of the previous income year (or financial year):
- •
- just before the start of the income year (or financial year)[7]
- •
- immediately before the start of the financial year[8], and
- •
- at the end of the previous income year.[9]
7. It is also the Commissioner's view that 'at the end of the [income] year'[10] means at the end of 30 June of the income year.
8. This means 'at the end' of an income year will be the same time as 'just before the start' of the next income year.
9. The components relevant to working out your total superannuation balance will only be reported by superannuation funds for one point in time each year, reflecting the amount at the end of 30 June for each year. This includes reporting the total superannuation balance value (TSB value)[11] of each superannuation interest.
Determining total superannuation balance
10. Your total superannuation balance[12] at a particular time is determined by:
- •
-
adding
the following amounts
- –
- Element 1 – the TSB value at that time of each relevant superannuation interest[13]; as well as your own superannuation interests, this includes certain other superannuation interests you are receiving (or may receive) a superannuation benefit from (see paragraphs 12 to 34 of this Ruling)
- –
- Element 2 – the amount of each roll-over superannuation benefit not already reflected in the TSB value of your superannuation interests[14] (see paragraphs 35 to 37 of this Ruling)
- –
- Element 3 – 'LRBA amounts'[15], in relation to a limited recourse borrowing arrangement (LRBA) of a small superannuation fund, including in a self managed superannuation fund (SMSF), in which you have a superannuation interest[16] (see paragraphs 38 to 43 of this Ruling), then
- •
- subtracting Element 4 – the sum of any structured settlement contributions[17] made in respect of you (see paragraphs 44 to 45 of this Ruling).
11. For most individuals[18], your total superannuation balance will be the sum of the TSB values of each relevant interest.
Element 1 – total superannuation balance value
12. The first element of your total superannuation balance is the TSB value of relevant interests at that time. This ensures that the value of each interest is included in your total superannuation balance.
13. The relevant superannuation interests included in your total superannuation balance are:
- •
- your superannuation interests[19]
- •
- superannuation interests of a deceased member that support a superannuation income stream for which you are the retirement phase recipient[20]
- •
- notional superannuation interests of yours that you are treated as having due to certain payment splits.[21]
14. These superannuation interests are included in your total superannuation balance, even if they are:
- •
- in a non-complying Australian superannuation fund, or
- •
- another type of excluded interest for Division 296 purposes.[22]
15. However, interests in foreign superannuation funds are not included in your total superannuation balance.[23]
16. The TSB value of all your superannuation interests is included in your total superannuation balance. Your superannuation interests are each of the following[24]:
- •
- an interest in a superannuation fund
- •
- an interest in an approved deposit fund
- •
- a retirement savings account
- •
- an interest in a superannuation annuity.
17. These interests are always included in your total superannuation balance, whether the interest is in the retirement phase[25] or not.
Retirement phase superannuation income streams paid after a member's death
18. The TSB value of a superannuation interest is included in your total superannuation balance where:
- •
- you are the retirement phase recipient of a superannuation income stream that is paid from the interest, and
- •
- the superannuation income stream is paid due to another person's death.[26]
19. The TSB value of the interest will be included in your total superannuation balance from the time you become a retirement phase recipient of the superannuation income stream. The time you become a retirement phase recipient depends on the facts and circumstances of each case.
20. Where you are the recipient of a reversionary death benefit income stream[27], it becomes payable to you automatically upon the member's death.[28] The TSB value of the interest will be included in your total superannuation balance from just after the time the member died.[29]
21. If you become entitled to a non-reversionary death benefit income stream, it is a new superannuation income stream. It will be included in your total superannuation balance when you become a retirement phase recipient, which will be determined using the existing rules.[30]
22. A non-reversionary death benefit income stream may become payable where a trustee decides to pay you a superannuation income stream after the member's death, and at the time of the member's death:
- •
- the interest was supporting a non-reversionary superannuation income stream, or
- •
- the interest was not supporting a superannuation income stream.
23. If you are only entitled to receive a superannuation lump sum from an interest due to the death of another person, the value of the interest is not included in your total superannuation balance.
24. Where a superannuation interest is subject to a payment split[31], a new interest can generally be created for the non-member spouse and their entitlement can be rolled over or transferred to it.
25. However, the governing rules of some superannuation funds do not allow a non-member spouse to become a member of the fund. In these cases, when a member spouse becomes entitled to receive a superannuation benefit from the superannuation interest, a portion will be payable to the non-member spouse.[32]
26. To reflect the fact that a portion of the interest is likely to be paid to the non-member spouse, the non-member spouse is taken to have a superannuation interest for the purposes of determining their total superannuation balance.[33] In this Ruling, this is referred to as a 'notional interest'. The inclusion of the notional interest, along with adjustments to the TSB value of the member interest connected to it, allows the total superannuation balance of the member and non-member spouses to reflect the terms of the payment split.
27. You will be taken to have a notional interest in a superannuation fund where[34]:
- •
- you are the non-member spouse in relation to a defined benefit superannuation interest
- •
- the interest is subject to a payment split but remains an interest of the member spouse
- •
- the governing rules of the superannuation plan that the member spouse's interest is within do not allow you to become a member of the plan, and
- •
- at least part of the amount you are entitled to has not been rolled over, transferred or allotted to another interest for your benefit.
28. Your notional interest will be treated as being a defined benefit interest[35] for total superannuation balance purposes, including for determining its TSB value.[36]
How to determine the total superannuation balance value of a particular interest
29. There are 2 different ways of determining the TSB value of a superannuation interest:
- •
- if the Income Tax Assessment (1997 Act) Regulations 2021 (ITAR (1997 Act) 2021) specifies a value or method for determining a value – its TSB value is that value or the value determined in accordance with the specified method[37], or
- •
- if no value or method for determining a value is specified in the regulations for the interest, its TSB value is what is known as its 'withdrawal benefit'.[38]
30. The 'withdrawal benefit' of your superannuation interest is the amount payable if you[39]:
- •
- had the right to cause the interest to cease at that time, and
- •
- voluntarily cause the interest to cease at that time.
31. The TSB value of most superannuation interests will be the withdrawal benefit.
32. For the following interests, the TSB value will always be the withdrawal benefit[40]:
- •
- Interests that are not in the retirement phase, other than where they are
- –
- a defined benefit interest[41]
- –
- an interest supporting an income stream that is a pension payable under sections 16 or 26 of the Australian Defence Force Cover Act 2015
- –
- an interest supporting an income stream that is a pension payable under section 123 of the Federal Circuit and Family Court of Australia Act 2021, or
- –
- an interest supporting a deferred superannuation income stream.[42]
- •
- Interests that are in the retirement phase[43] and support one of the following superannuation income streams[44]
33. Regulations have been made which specify the TSB value of other interests or a method to determine the TSB value. How the TSB value will be determined for a particular interest depends on various factors, including:
- •
- the time the TSB value is to be determined, as different methods may apply to the interest just before 1 July 2026 compared to after that time
- •
- whether or not the interest is a defined benefit interest
- •
- whether or not the interest is in the retirement phase
- •
- if the interest is in the retirement phase, the type of superannuation income stream it is supporting, and
- •
- the characteristics of the superannuation fund and interest, including whether it is eligible to use particular valuation methods.
34. Draft Law Companion Ruling LCR 2026/D6 Total superannuation balance value provides further details on the methods that may be used to determine the TSB value of superannuation interests and when they apply. This includes special rules for notional interests (and the member spouse's interest that relates to the notional interest).
Element 2 – roll-over superannuation benefits
35. The second element, if applicable, is the amount of each roll-over superannuation benefit[51] that is not reflected in the TSB value of a superannuation interest under Element 1.
36. This ensures that amounts that are not included in the TSB value of any of your relevant superannuation interests because a roll-over superannuation benefit was paid shortly before the end of the financial year are included in your total superannuation balance.
37. The amount of a roll-over superannuation benefit is included in your total superannuation balance at a particular time if it:
- •
- was paid at or before that time, and
- •
- is received after that time by
- –
- the complying superannuation plan, or
- –
- the entity from which the superannuation annuity is being purchased, and
- •
- is not reflected in the TSB value of a superannuation interest under Element 1 at that particular time.[52]
38. The third element, if applicable, is the outstanding balance of an LRBA amounts[53], subject to the further conditions as outlined in paragraphs 40 to 42 of this Ruling. This element ensures that your total superannuation balance accurately reflects the overall values of the assets in a superannuation fund that support your superannuation interests.
39. Your total superannuation balance determined for Division 296 purposes does not include the outstanding balance of any LRBA.[54]
40. An amount is only included in this element where an LRBA was entered into on or after 1 July 2018[55] by the trustee of a small superannuation fund, including an SMSF.
41. However, an LRBA that was entered into on or after 1 July 2018 is treated as being entered into before that date if[56]:
- •
- it is the refinancing of a borrowing that was made under an LRBA contract entered into before 1 July 2018
- •
- the refinanced LRBA is secured by the same asset or assets as the original LRBA, and
- •
- the amount borrowed under the refinanced LRBA at the time it is entered into is equal to or less than the outstanding balance of the borrowing under the original LRBA just before the refinancing.
42. An LRBA amount will be included in your total superannuation balance where an LRBA was entered into on or after 1 July 2018 (excluding those outlined in paragraph 41 of this Ruling) if:
- •
- you have satisfied one or more conditions of release relating to retirement, terminal medical condition, permanent incapacity or attaining age 65 (whether at or before that time)[57], or
- •
- the lender is an associate of the superannuation provider.[58]
43. The LRBA amount included in your total superannuation balance is equal to the proportion of the outstanding balance of the LRBA which relates to your share of the total superannuation interests that are supported by the asset or assets which are subject to the LRBA[59]:
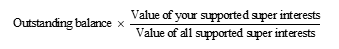
Element 4 – subtract any structured settlement contributions
44. The last element of calculating your total superannuation balance at a particular time is to reduce the sum of Elements 1 to 3 by the sum of any structured settlement contributions[60] made at or before the particular time in respect of you.[61]
45. This ensures any structured settlement contributions are excluded from your total superannuation balance.
Example 1 – account-based pension and accumulation account
46. On 1 October 2026, Simon retires from employment at age 60. At the time of his retirement, he has $2,500,000 in the Gravitude Superannuation Fund and no other superannuation interests.
47. On 1 December 2026, Simon commences an account-based pension with $2,000,000 from his superannuation interest (the account-based pension interest). The balance of his superannuation remains in another interest within the same fund (the accumulation interest).
48. At the end of 30 June 2027:
- •
- the TSB value of Simon's account-based pension interest is $2,100,000
- •
- the TSB value of Simon's accumulation interest is $510,000.
49. To work out Simon's total superannuation balance just before 1 July 2027, the value of Elements 1 to 4 must be determined. Assuming he has no roll-over superannuation benefits, relevant LRBA amounts or structured settlement contributions:
- •
-
Element 1
– TSB value
- –
- TSB values of relevant interests are $2,100,000 + $510,000 = $2,610,000
- –
- this includes the TSB value of Simon's account-based pension interest and his accumulation interest
- •
- Element 2 – roll-over superannuation benefits = $0
- •
- Element 3 – LRBA amounts = $0
- •
- Element 4 – structured settlement contributions = $0.
50. Simon's total superannuation balance is calculated by adding Elements 1, 2 and 3, then subtracting Element 4:
$2,610,000 + $0 + $0 − $0 = $2,610,000
51. Simon's total superannuation balance just before 1 July 2027 is, therefore, $2,610,000.
Example 2 – total superannuation balance of death benefit income stream recipient
52. Wallace and Tiffany are married, and members and trustees of the Raclette SMSF. Wallace is also a member of an Australian Prudential Regulation Authority-regulated fund (APRA fund).
53. Wallace retires in 2020. On 1 July 2026, he has the following superannuation income streams:
- •
- a lifetime pension supported by his interest in the APRA fund; the lifetime pension is reversionary and becomes payable to Tiffany on Wallace's death
- •
- an account-based pension supported by his interest in the Raclette SMSF; the account-based pension is not reversionary.
54. Wallace does not have a binding death benefit nomination in place for his interest in the Raclette SMSF.
55. Tiffany has not retired and her superannuation interest in the Raclette SMSF is entirely in the accumulation phase. She is not a member of any other superannuation funds.
56. On 15 May 2027, Wallace dies. As the pension payable from the APRA fund is reversionary, Tiffany automatically becomes entitled to receive payments from Wallace's lifetime pension at the time of his death[62]. However, at the end of the income year, no decisions have been made regarding paying Wallace's benefits in the Raclette SMSF.
Tiffany's total superannuation balance just before 1 July 2027
57. At the end of 30 June 2027, Wallace and Tiffany's superannuation interests are valued as follows:
- •
- the TSB value of the interest supporting the lifetime pension is $1,500,000
- •
- the TSB value of Wallace's interest in the Raclette SMSF is $2,000,000
- •
- the TSB value of Tiffany's interest is $1,000,000.
58. To work out Tiffany's total superannuation balance just before 1 July 2027, the value of Elements 1 to 4 must be determined. Assuming she has no roll-over superannuation benefits, relevant LRBA amounts or structured settlement contributions:
- •
-
Element 1
– TSB value
- –
- TSB values of relevant interests are $1,500,000 + $1,000,000 = $2,500,000
- –
- this includes the TSB value of the reversionary lifetime pension that Tiffany is receiving, as well as Tiffany's own accumulation interest; Wallace's other interest is not included in Tiffany's total superannuation balance as she is not receiving a retirement phase superannuation income stream from it
- •
- Element 2 – roll-over superannuation benefits = $0
- •
- Element 3 – LRBA amounts = $0
- •
- Element 4 – structured settlement contributions = $0.
59. Tiffany's total superannuation balance is calculated by adding Elements 1, 2 and 3, then subtracting Element 4:
$2,500,000 + $0 +$0 − $0 = $2,500,000
60. Tiffany's total superannuation balance just before 1 July 2027 is, therefore, $2,500,000.
Tiffany's total superannuation balance just before 1 July 2028
61. On 1 August 2027, Tiffany:
- •
- becomes the retirement phase recipient of an account-based pension from Wallace's interest in the Raclette SMSF; the withdrawal benefit at commencement is $600,000
- •
- receives a superannuation lump sum of $1,400,000, representing the balance of Wallace's superannuation interest in the Raclette SMSF.
62. Just before 1 July 2028, Wallace and Tiffany's superannuation interests are valued as follows:
- •
- the TSB value of the interest supporting the lifetime pension is $1,450,000
- •
- the TSB value of the interest supporting the account-based pension is $650,000
- •
- the TSB value of Tiffany's accumulation interest is $1,050,000.
63. The $1,400,000 superannuation lump sum Tiffany received is no longer in the superannuation system and is therefore not relevant to the calculation of her total superannuation balance just before 1 July 2028.
64. To work out Tiffany's total superannuation balance just before 1 July 2028, the value of Elements 1 to 4 must be determined. Assuming she has no roll-over superannuation benefits, relevant LRBA amounts or structured settlement contributions:
- •
-
Element 1
– TSB value
- –
- TSB values of relevant interests are $1,450,000 + $650,000 + $1,050,000 = $3,150,000
- –
- this includes the TSB value of both superannuation income streams that Tiffany is receiving due to Wallace's death, as well as her own accumulation interest
- •
- Element 2 – roll-over superannuation benefits = $0
- •
- Element 3 – LRBA amounts = $0
- •
- Element 4 – structured settlement contributions = $0.
65. Tiffany's total superannuation balance is calculated by adding Elements 1, 2 and 3, then subtracting Element 4:
$3,150,000 + $0 + $0 − $0 = $3,150,000
66. Tiffany's total superannuation balance just before 1 July 2028 is, therefore, $3,150,000.
Example 3 – roll-over superannuation benefit
67. On 29 June 2027, Max has $200,000 in the Ingenui Superannuation Fund. She also has $1,500,000 in the Perpendiculous Superannuation Fund. Neither superannuation interest is in the retirement phase.
68. Max decides to combine her superannuation and requests that the Ingenui Superannuation Fund roll over her benefits to the Perpendiculous Superannuation Fund.
69. The roll-over superannuation benefit is paid by the Ingenui Superannuation Fund on 29 June 2027. It is received by the Perpendiculous Superannuation Fund on 1 July 2027. The roll-over superannuation benefit is not reflected in the TSB value of the superannuation interests in either fund at the end of 30 June 2027.
70. To work out Max's total superannuation balance just before 1 July 2027, the value of Elements 1 to 4 must be determined. Assuming that Max does not have any relevant LRBA amounts or structured settlement contributions and no further earnings have been added into her interest in the Perpendiculous Superannuation Fund:
- •
-
Element 1
– TSB value
- –
- TSB value of relevant interest = $1,500,000
- –
- this is the value of the interest held in the Perpendiculous Superannuation Fund as at the end of 30 June 2027; Max no longer has an interest in the Ingenui Superannuation Fund at that time
- •
-
Element 2
– roll-over superannuation benefits
- –
- relevant roll-over superannuation benefits = $200,000
- –
- this is the value of the roll-over superannuation benefit that is not reflected in the TSB value of Max's superannuation interests
- •
- Element 3 – LRBA amounts = $0
- •
- Element 4 – structured settlement contributions = $0.
71. Max's total superannuation balance is calculated by adding Elements 1, 2 and 3, then subtracting Element 4:
$1,500,000 + $200,000 + $0 − $0 = $1,700,000
72. Max's total superannuation balance just before 1 July 2027 is, therefore $1,700,000.
Example 4 – LRBA amount – condition of release with a nil cashing restriction
73. Harry and Beth are members and trustees of their SMSF, the Megaplex Superannuation Fund. Harry is 65 years old and Beth is 60 years old. Neither Harry nor Beth holds an interest in any other superannuation fund.
74. On 28 June 2027, the value of Harry's superannuation interest in the Megaplex Superannuation Fund is $600,000 and the value of Beth's superannuation interest is $400,000. The interests are held entirely in cash (for a total of $1,000,000) and are not in the retirement phase.
75. On 29 June 2027, the Megaplex Superannuation Fund enters into an LRBA (covered by section 67A of the SISA) with a commercial lender to borrow $1,000,000. It uses the $1,000,000 it borrows, together with $500,000 that it holds in cash, to purchase a commercial property for $1,500,000.
76. Of the $500,000 cash used to purchase the commercial property, 60% ($300,000) was supporting Harry's superannuation interest and the other 40% ($200,000) was supporting Beth's superannuation interest. These percentages also reflect the extent to which the commercial property supports Harry and Beth's superannuation interests.
77. At the end of 30 June 2027, the Megaplex Superannuation Fund has total assets of $2,000,000, made up of the market value of the commercial property of $1,500,000 and $500,000 in cash. The Megaplex Superannuation Fund also has a liability of $1,000,000 (the outstanding balance of the LRBA).
78. At the end of 30 June 2027, Beth has never satisfied any of the conditions of release relating to retirement, terminal medical condition, permanent incapacity or attaining age 65.
Harry's total superannuation balance
79. To work out Harry's total superannuation balance just before 1 July 2027, the value of Elements 1 to 4 must be determined. Assuming that Harry does not have any roll-over superannuation benefits or structured settlement contributions:
- •
-
Element 1
– TSB value
- –
- TSB value of relevant interest = $600,000
- –
- this consists of $300,000 cash and $300,000 which represents Harry's share of the net value of the property (60% of the $500,000[63])
- •
- Element 2 – roll-over superannuation benefits = $0
- •
-
Element 3
– LRBA amounts = $600,000
- •
- Element 4 – structured settlement contributions = $0
80. Harry's total superannuation balance is calculated by adding the amounts at Elements 1, 2 and 3, then subtracting Element 4:
$600,000 + $0 + $600,000 − $0 = $1,200,000
81. Harry's total superannuation balance just before 1 July 2027 is, therefore, $1,200,000.
82. For Division 296 purposes, Harry's total superannuation balance is $600,000 as the LRBA amount is excluded.[66]
Beth's total superannuation balance
83. To work out Beth's total superannuation balance just before 1 July 2027, the value of Elements 1 to 4 must be determined. Assuming that Beth does not have any roll-over superannuation benefits or structured settlement contributions:
- •
-
Element 1
– TSB value
- –
- TSB value of relevant interest = $400,000
- –
- this consists of $200,000 cash and $200,000 which represents her share of the net value of the property (40% of the $500,000)[67]
- •
- Element 2 – roll-over superannuation benefits = $0
- •
-
Element 3
– LRBA amounts = $0
- –
- there is no LRBA amount to be included, as Beth has never satisfied a relevant condition of release and the lender is not an associate of the superannuation fund
- •
- Element 4 – structured settlement contributions = $0.
84. Beth's total superannuation balance is calculated by adding the amounts at Elements 1, 2 and 3, then subtracting Element 4:
$400,000 + $0 + $0 − $0 = $400,000
85. Beth's total superannuation balance just before 1 July 2027 is, therefore, $400,000.
Example 5 – LRBA amount – lender is an associate of the superannuation fund
86. Matt and Jodie are the trustees and members of their SMSF, the Mesablanca Superannuation Fund). They do not have an interest in any other superannuation fund.
87. On 31 July 2026, the value of Matt's superannuation interest in the Mesablanca Superannuation Fund is $450,000 and the value of Jodie's superannuation interest is $150,000. Both hold superannuation interests that are not in the retirement phase and are held entirely in cash (for a total of $600,000).
88. Matt and Jodie, as trustees, wish to diversify the Mesablanca Superannuation Fund's assets, in accordance with the fund's investment strategy, and decide to purchase a parcel of listed shares with a market value of $500,000. On 1 August 2026, the Mesablanca Superannuation Fund enters into an LRBA covered by section 67A of the SISA, with Matt to borrow $250,000 under a 7-year loan term at 11.35%[68] per annum, with monthly repayments. The Mesablanca Superannuation Fund uses the $250,000 it borrows, together with $250,000 it holds in cash, to purchase the listed shares for $500,000.
89. Of the cash used, 75% ($187,500) was supporting Matt's superannuation interest and 25% ($62,500) was supporting Jodie's interest. These percentages also reflect the extent to which the listed shares support Matt and Jodie's superannuation interests.
90. At the end of 30 June 2027, the market value of the listed shares held by the Mesablanca Superannuation Fund is $520,000, and it has a liability in respect of the LRBA of $227,364. The Mesablanca Superannuation Fund also has $355,000 in cash, which is referrable to Matt and Jodie's interests as follows:
- •
- Matt = $266,250 cash
- •
- Jodie = $88,750 cash.
91. Matt is an associate of the Mesablanca Superannuation Fund.[69]
Matt's total superannuation balance
92. To work out Matt's total superannuation balance just before 1 July 2027, the value of Elements 1 to 4 must be determined. Assuming that Matt does not have any roll-over superannuation benefits or structured settlement contributions:
- •
-
Element 1
– TSB value
- –
- TSB value of relevant interest = $485,727
- –
- this consists of $266,250 cash and $219,477 which represents 75% of the net value of listed shares (75% of $292,636)[70]
- •
- Element 2 – roll-over superannuation benefits = $0
- •
-
Element 3
– LRBA amounts = $170,523
- –
- an LRBA amount is included as the LRBA lender is an associate of the Mesablanca Superannuation Fund; it is determined for Matt as 75% of the outstanding balance of the LRBA (equal to $227,364)
- •
- Element 4 – structured settlement contributions = $0.
93. Matt's total superannuation balance is calculated by adding the amounts at Elements 1, 2 and 3, then subtracting Element 4:
$485,727 + $0 + $170,523 − $0 = $656,250
94. Matt's total superannuation balance just before 1 July 2027 is $656,250.
95. For Division 296 purposes, Matt's total superannuation balance is $485,727 as the LRBA amount is excluded.[71]
Jodie's total superannuation balance
96. In order to work out Jodie's total superannuation balance just before 1 July 2027, the value of Elements 1 to 4 must be determined. Assuming that Jodie does not have any roll-over superannuation benefits or structured settlement contributions:
- •
-
Element 1
– TSB value
- –
- TSB value of relevant interest = $161,909
- –
- this consists of $88,750 cash and $73,159 which represents 25% of the net value of the listed shares (25% of $292,636)[72]
- •
- Element 2 – roll-over superannuation benefits = $0
- •
-
Element 3
– LRBA amounts = $56,841
- –
- an LRBA amount is included as the LRBA lender is an associate of the Mesablanca Superannuation Fund; it is determined as 25% of the outstanding balance of the LRBA (equal to $227,364)
- •
- Element 4 – structured settlement contributions = $0.
97. Jodie's total superannuation balance is calculated by adding the amounts at Elements 1, 2 and 3, then subtracting Element 4:
$161,909 + $0 + $56,841 − $0 = $218,750
98. Jodie's total superannuation balance just before 1 July 2027 is $218,750.
99. For Division 296 purposes, Jodie's total superannuation balance is $161,909 as the LRBA amount is excluded.[73]
Example 6 – structured settlement contribution
100. Jack has an interest in the Camembert Superannuation Fund, which is in the accumulation phase. He has no other superannuation interests.
101. On 12 October 2026, Jack is awarded a structured settlement of $1,800,000. He contributes this payment to his superannuation interest, which brings the balance of that interest to $2,000,000.
102. On 30 November 2026, Jack commences an account-based pension of $1,800,000 from the Camembert Superannuation Fund. The remainder of his superannuation interest continues to be held in an accumulation interest in the Camembert Superannuation Fund.
103. At the end of 30 June 2027, the TSB values of Jack's interests are:
- •
- TSB value of account-based pension interest = $1,650,000
- •
- TSB value of accumulation interest = $250,000.
104. To work out Jack's total superannuation balance just before 1 July 2027, the value of Elements 1 to 4 must be determined. Assuming that Jack does not have any roll-over superannuation benefits or relevant LRBA amounts:
- •
-
Element 1
–TSB value
- –
- TSB values of relevant superannuation interests are $250,000 + $1,650,000 = $1,900,000
- –
- this is the sum of Jack's interest that is supporting an account-based pension, and his accumulation interest in the fund
- •
- Element 2 – roll-over superannuation benefits = $0
- •
- Element 3 – LRBA amounts = $0
- •
- Element 4 –structured settlement contribution = $1,800,000.
105. Jack's total superannuation balance is calculated by adding the amounts at Elements 1, 2 and 3, then subtracting Element 4:
$1,900,000 + $0 + $0 − $1,800,000 = $100,000
106. Jack's total superannuation balance just before 1 July 2027 is $100,000.
107. When the final Ruling is issued, it is proposed to apply from 30 June 2026.
Commissioner of Taxation
4 November 2026
Appendix 1 – Relevance of total superannuation balance
|
This Appendix is provided as information to help you understand the different contexts in which total superannuation balance is relevant. It does not form part of the proposed binding public ruling.
|
Provisions for which total superannuation balance is relevant
108. Subject to 2 exceptions[74], you are liable to pay Division 296 tax for an income year if you have taxable superannuation earnings for the year.[75] You have taxable superannuation earnings for an income year if your[76]:
- •
- total superannuation balance exceeds the large superannuation balance threshold (LSBT)[77] for the year, and
- •
- total superannuation earnings[78] are greater than nil.
109. The amount of your taxable superannuation earnings is determined using a percentage of your total superannuation earnings. The percentage is equal to the proportion of your relevant total superannuation balance that exceeds the LSBT.[79]
110. Where relevant, Division 296 tax also applies at a higher rate to the percentage of your total superannuation earnings that equates to the proportion of your total superannuation balance that exceeds the very large superannuation balance threshold (VLSBT).[80]
Eligibility for unused concessional contributions cap carry forward
111. If your total superannuation balance is less than $500,000 just before the start of the financial year, your concessional contributions cap may be increased.[81] For this to occur, you must also have unused concessional contributions cap for one or more of the previous 5 financial years.[82]
Non-concessional contributions cap, including bringing forward your non-concessional contributions cap
112. If, immediately before the start of the financial year, your total superannuation balance is below the general transfer balance cap[83], your non-concessional contributions cap will be 4 times your concessional contributions cap (not taking into account increases under the concessional cap carry forward measure) for the year.[84]
113. You may also be eligible to bring forward your non-concessional contributions cap of 2 or 3 times the annual non-concessional cap, depending on your total superannuation balance.[85]
114. If your total superannuation balance equals or exceeds the general transfer balance cap just before the start of the financial year, your non-concessional contributions cap will be nil.
Eligibility for work test exemption
115. If you make a personal superannuation contribution in the period starting the day you turn 67 years old and ending on the 28th day after the end of the month that you turn 75 years old, to claim a deduction for the contribution you must satisfy either the work test or the one-off work test exemption.
116. In addition to other eligibility requirements[86], you will be eligible for the work test exemption if your total superannuation balance is below $300,000 at the end of the previous income year.[87 ]
Eligibility for the government co-contribution
117. In addition to other eligibility requirements[88 ], you will be eligible for the government co-contribution in an income year if[89]:
- •
- your non-concessional contributions for the financial year corresponding to the income year do not exceed your non-concessional contributions cap for the financial year, and
- •
- immediately before the start of that financial year, your total superannuation balance is less than the general transfer balance cap[90] for that financial year.
Eligibility for the tax offset for spouse contributions
118. In addition to other eligibility requirements[91], you will not be entitled to the tax offset for superannuation contributions made for your spouse's benefit if[92]:
- •
- your spouse's non-concessional contributions for the financial year that corresponds to the income year exceeds their non-concessional contributions cap for the financial year, or
- •
- immediately before the start of the financial year, your spouse's total superannuation balance equals or exceeds the general transfer balance cap for the financial year.
119. Small superannuation funds cannot use the segregated method to determine their ECPI for an income year if they have disregarded small fund assets[93], which will occur where[94]:
- •
- at a time during the income year, there is at least one superannuation interest in the fund that is in retirement phase
- •
- just before the start of the income year, a person has a total superannuation balance that exceeds $1.6 million[95] and they are a retirement phase recipient of a superannuation income stream, whether or not that superannuation income stream is within the small superannuation fund, and
- •
- at a time during the income year, the person has a superannuation interest in the small superannuation fund (it does not have to be the interest referred to in the first dot point of this paragraph).
120. However, if all the assets of the small superannuation fund would be supporting retirement phase superannuation interests at all times during the income year, apart from the fact they have disregarded fund assets, the fund may still use the segregated method to determine their ECPI.[96]
Appendix 2 – Your comments
121. You are invited to provide comments on this draft Ruling. Forward your comments to the contact officer by the due date.
122. A compendium of comments is prepared as part of the finalisation of this Ruling. An edited version of the compendium (with names and identifying information removed) is published to the ATO Legal database on ato.gov.au.
123. Advise the contact officer if you do not wish for your comments to be included in the edited compendium.
| Due date: | 18 December 2026 |
| Contact officer: | Sharon Russell |
| Email: | BTSCPAG@ato.gov.au |
© AUSTRALIAN TAXATION OFFICE FOR THE COMMONWEALTH OF AUSTRALIA
You are free to copy, adapt, modify, transmit and distribute this material as you wish (but not in any way that suggests the ATO or the Commonwealth endorses you or any of your services or products).
Footnotes
For readability, all further references to 'this Ruling' refer to the Ruling as it will read when finalised. Note that this Ruling will not take effect until finalised.
Under section 307-230 of the Income Tax Assessment Act 1997.
See Appendix 1 to this Ruling for more information.
Tax imposed by the Superannuation (Building a Stronger and Fairer Super System) Imposition Act 2026 under Division 296 of the Income Tax Assessment Act 1997 (ITAA 1997).
'Small superannuation fund' is defined in subsection 995-1(1) of the ITAA 1997 as a complying superannuation fund with no more than 6 members. This includes self managed superannuation funds, as defined in subsection 10(1) of the Superannuation Industry (Supervision) Act 1993 (SISA).
The total superannuation balance of a small superannuation fund's members may affect which method can (or must) be used to determine the fund's ECPI for a year. See Appendix 1 to this Ruling for more information.
For example, as used in paragraph 291-20(3)(b) for determining your eligibility for the carry forward of your unused concessional contributions cap.
For example, as used in subsection 290-230(4A) for determining your eligibility for the tax offset for spouse contributions.
As used in subparagraph 290-165(1A)(b)(ii) for determining your eligibility for the work test exemption.
For example, as used in paragraph 296-40(1)(a) in determining if you have taxable superannuation earnings for a year (used to determine your Division 296 tax liability).
'Total superannuation balance value' is defined in section 307-230A. It is the value of a superannuation interest at a particular time determined for the purposes of calculating your total superannuation balance. See paragraphs 12 to 15 and 29 to 34 of this Ruling.
Determined under section 307-230. However, in determining your potential liability to Division 296 tax, after you die your total superannuation balance for the purposes of sections 296-40 and 296-45 is taken to be nil (section 296-50).
Paragraph 307-230(1)(a) and subsection 307-230(3). However, under paragraph 307-230(1)(a), interests in foreign superannuation funds are expressly excluded from your total superannuation balance.
Paragraph 307-230(1)(c). 'Roll-over superannuation benefit' is defined in section 306-10.
As defined in section 307-231. An LRBA amount only arises in relation to an LRBA in the circumstances outlined in subsection 307-231(1).
Paragraph 307-230(1)(d) and section 307-231. When determining your total superannuation balance for Division 296 purposes, an LRBA amount included in your total superannuation balance under paragraph 307-230(1)(d) is disregarded under section 296-260.
Subsection 307-230(2). Structured settlement contribution has the meaning given by section 294-80.
That is, those individuals who do not have any of Elements 2 to 4 (listed in paragraph 10 of this Ruling).
Subparagraph 307-230(1)(a)(i).
Subparagraph 307-230(1)(a)(ii).
Subparagraph 307-230(1)(a)(i) and subsection 307-230(3).
Subsection 296-55(2) operates to make relevant superannuation earnings (used to determine Division 296 tax liabilities) nil for excluded interests. The table in subsection 296-55(3) provides an exhaustive list of excluded interests and includes interests in non-complying Australian superannuation funds. However, there is nothing in section 307-230 or any other provision that excludes these interests in calculating your total superannuation balance (other than interests in foreign superannuation funds, as mentioned in paragraph 15 of this Ruling).
Subsection 307-230(1).
Definition of 'superannuation interest' in subsection 995-1(1).
Subsection 995-1(1) defines when a superannuation interest is in the retirement phase.
Subparagraph 307-230(1)(a)(ii).
Paragraphs 10 to 18 of Law Companion Ruling LCR 2017/3 Superannuation reform: Superannuation death benefits and the transfer balance cap provide guidance on the meaning of reversionary and non-reversionary death benefit income streams.
See paragraphs 125 and 126 of Taxation Ruling TR 2013/5 Income tax: when a superannuation income stream commences and ceases.
Subparagraph 307-230(1)(a)(ii). However, for transfer balance account purposes, the transfer balance credit will arise 12 months after a superannuation income stream commences. See paragraph 34 of Law Companion Ruling LCR 2016/9 Superannuation reform: transfer balance cap and paragraphs 27 to 31 of LCR 2017/3.
Paragraphs 9 to 12 of TR 2013/5 provide guidance about when a superannuation income stream commences.
Defined in subregulation 1.03(1) of the Superannuation Industry (Supervision) Regulations 1994 (SISR) as meaning a payment split within the meaning of Parts VIIIB or VIIIC of the Family Law Act 1975.
However, there may be exceptions to this general rule for some superannuation benefits under the Family Law Act 1975 or the Family Law (Superannuation) Regulations 2025.
Subsection 307-230(4) lists the provisions for which the non-member spouse is taken to have a notional interest. These are subsection 307-230(1) (used for determining their total superannuation balance), section 307-230A (used to determine the total superannuation balance value of an interest) and the Division 296 tax law as defined in subsection 995-1(1).
Subsection 307-230(3) of the ITAA 1997 and section 307-230.01 of the Income Tax Assessment (1997 Act) Regulations 2021 (ITAR (1997 Act) 2021).
Subsection 307-230.01(3) of the ITAR (1997 Act) 2021.
It is also treated as a defined benefit interest for Division 296 tax law as defined in subsection 995-1(1) (paragraph (a) of the definition of 'Division 296 tax law' in subsection 995-1(1) includes the provisions of the ITAA 1997 so far as they relate to Division 296 tax).
Paragraph 307-230A(1)(a).
Paragraph 307-230A(1)(b). See also paragraph 1.49 of the Explanatory Memorandum to the Treasury Laws Amendment (Building a Stronger and Fairer Super System) Bill 2026 and the Superannuation (Building a Stronger and Fairer Super System) Imposition Bill 2026.
Paragraph 307-230A(1)(b).
The withdrawal benefit is used for these interests as there are no regulations that specify how to determine their TSB value at any time. The superannuation income streams in the retirement phase listed are specifically excluded from using the TSB value methods in the regulations by subsection 307-230A.02(5) of the ITAR (1997 Act) 2021.
As defined in section 291-175.
Subsection 307-80(2) explains when a deferred superannuation income stream is in the retirement phase.
Some superannuation income streams may not be in the retirement phase, including transition to retirement pensions. See subsection 307-80(3) and paragraph 15 of LCR 2016/9.
Subsections 307-230A.02(1) and (5) of the ITAR (1997 Act) 2021.
Defined in subsection 995-1(1) as an immediate annuity that satisfies the requirements of subregulation 1.05(4) of the SISR.
Includes both current pensions that satisfy the requirements of subregulation 1.06(4) of the SISR (definition in section 995-1(1)) and those within the meaning of the Retirement Savings Account Regulations 1994 (RSA Regulations).
Defined in subsection 995-1(1) as having the meaning given by the SISR.
Within the meaning of the SISR and the RSA Regulations.
Within the meaning of the SISR.
Within the meaning of the SISR and the RSA Regulations.
As defined in section 306-10.
Paragraph 307-230(1)(c).
LRBAs are only allowed where they are covered by the exception in subsection 67A(1) of the SISA. The amount included in your total superannuation balance is determined under section 307-231 and is included in your total superannuation balance under paragraph 307-230(1)(d).
Section 296-260.
Subsection 307-231(1) of the Income Tax (Transitional Provisions) Act 1997.
Subsection 307-231(2) of the Income Tax (Transitional Provisions) Act 1997.
Subparagraph 307-231(1)(e)(i) and paragraph 307-80(2)(c). The relevant conditions of release are the following items in the table in Part 1 of Schedule 1 to the SISR: table item 101 (retirement), table item 102A (terminal medical condition), table item 103 (permanent incapacity) and table item 106 (attaining age 65).
Subparagraph 307-231(1)(e)(ii). The definition of an 'associate of a trustee' is in subsection 318(3) of the Income Tax Assessment Act 1936 (ITAA 1936).
Subsection 307-231(3). It should be noted that Part IVA of the ITAA 1936 may apply where a scheme is entered into to manipulate the allocation of assets that are subject to LRBAs against particular superannuation interests at a particular time (see paragraph 3.24 of the Explanatory Memorandum to the Treasury Laws Amendment (2018 Superannuation Measures No.1) Bill 2019). Part IVA applies to a scheme if a tax benefit has been obtained in connection with the scheme and the main purpose of a person who participated in the scheme, or a part of it, was to enable a taxpayer to obtain that tax benefit.
As defined in subsection 294-80(2).
Subsection 307-230(2).
However, as it is a reversionary income stream it will not be included in Tiffany's transfer balance account until 12 months after Wallace's death. See footnote 29 of this Ruling.
The net value of the property is its market value less the outstanding value of the LRBA ($1,500,000 minus $1,000,000); 60% of this amount is included in Harry's TSB value for the interest, which is the percentage that the commercial property supports his superannuation interest.
Subparagraphs 307-231(1)(e)(i) and 307-80(2)(c)(iv). See further at paragraph 42 of this Ruling.
Determined using the formula in subsection 307-231(3). See further at paragraph 43 of this Ruling.
See section 296-260 and paragraph 39 of this Ruling.
The net value of the property is its market value less the outstanding value of the LRBA ($1,500,000 minus $1,000,000); 40% of this amount is included in Beth's TSB value for the interest, which is the percentage that the commercial property supports Beth's superannuation interest.
The terms of the loan meet the requirements of Practical Compliance Guideline PCG 2016/5: Income tax − arm's length terms for limited recourse borrowing arrangements established by self-managed superannuation funds.
As an entity that benefits under the trust, see paragraph 318(3)(a) of the ITAA 1936.
The net value of the listed shares is determined as the market value less the amount owing on the LRBA ($520,000 − $227,364 = $292,636); 75% of this amount is included in Matt's TSB value for the interest, which is the percentage that the listed shares support Matt's superannuation interest.
See section 296-260 and paragraph 39 of this Ruling.
The net value of the listed shares is determined as the market value less the amount owing on the LRBA ($520,000 − $227,364 = $292,636); 25% of this amount is included in Jodie's TSB value for the interest, which is the percentage that the listed shares support Jodie's superannuation interest.
See section 296-260 and paragraph 39 of this Ruling.
Child recipients of superannuation income streams (section 296-20) and if a structured settlement contribution is made in respect of you in that year or in any earlier income year (section 296-25).
Section 296-15.
Subsection 296-40(1).
Section 296-30. For the 2026-27 income year, the LSBT is $3 million. For later income years, the LSBT will be indexed to the consumer price index (CPI) annually, in $150,000 increments (see sections 960-265 and 960-285).
Section 296-55.
Subsections 296-40(2) and (3).
Section 296-35 and section 296-45. For the 2026-27 income year, the VLSBT is $10 million. For later income years, the VLSBT will be indexed to the CPI annually, in $500,000 increments (see sections 960-265 and 960-285).
Paragraph 291-20(3)(b).
Paragraph 291-20(3)(c).
'General transfer balance cap' is defined in subsection 294-35(3). For further information on the transfer balance cap, see LCR 2016/9.
Paragraph 292-85(2)(a).
Subsections 292-85(3) to (7).
Paragraph 290-165(1A)(b).
Subparagraph 290-165(1A)(b)(ii).
Eligibility requirements for the government co-contribution are outlined in subsection 6(1) of the Superannuation (Government Co-contribution for Low Income Earners) Act 2003.
Paragraphs 6(1)(da) and (db) of the Superannuation (Government Co-contribution for Low Income Earners) Act 2003.
Section 56 of the Superannuation (Government Co-contribution for Low Income Earners) Act 2003 states that 'general transfer balance cap' has the same meaning as in the ITAA 1997.
Section 290-230.
Subsection 290-230(4A).
Subsection 295-385(7).
Section 295-387.
Subparagraph 295-387(2)(c). This amount is not indexed.
Subsection 295-387(3).
Not previously issued as a draft
References
ATO references:
NO 1-13FM7710
Related Rulings/Determinations:
LCR 2016/9
LCR 2017/3
TR 2013/5
LCR 2026/D6
Legislative References:
Australian Defence Force Cover Act 2015 16
Australian Defence Force Cover Act 2015 26
Family Law (Superannuation) Regulations 2025
Federal Circuit and Family Court of Australia Act 2021 123
ITAA 1936 318(3)
ITAA 1936 318(3)(a)
ITAA 1936 Part IVA
ITAA 1997 290-165(1A)(b)
ITAA 1997 290-165(1A)(b)(ii)
ITAA 1997 290-230
ITAA 1997 290-230(4A)
ITAA 1997 291-20(3)(b)
ITAA 1997 291-20(3)(c)
ITAA 1997 291-175
ITAA 1997 292-85(2)(a)
ITAA 1997 292-85(2)(b)
ITAA 1997 292-85(3)
ITAA 1997 292-85(4)
ITAA 1997 292-85(5)
ITAA 1997 292-85(6)
ITAA 1997 292-85(7)
ITAA 1997 294-35
ITAA 1997 294-80(2)
ITAA 1997 295-385(7)
ITAA 1997 295-387
ITAA 1997 295-387(3)
ITAA 1997 Division 296
ITAA 1997 296-15
ITAA 1997 296-20
ITAA 1997 296-25
ITAA 1997 296-30
ITAA 1997 296-35
ITAA 1997 296-40
ITAA 1997 296-40(1)
ITAA 1997 296-40(1)(a)
ITAA 1997 296-40(2)
ITAA 1997 296-40(3)
ITAA 1997 296-45
ITAA 1997 296-55
ITAA 1997 296-55(2)
ITAA 1997 296-55(3)
ITAA 1997 296-260
ITAA 1997 306-10
ITAA 1997 307-80(2)
ITAA 1997 307-80(2)(c)
ITAA 1997 307-80(2)(c)(iv)
ITAA 1997 307-80(3)
ITAA 1997 307-230
ITAA 1997 307-230(1)
ITAA 1997 307-230(1)(a)
ITAA 1997 307-230(1)(a)(i)
ITAA 1997 307-230(1)(a)(ii)
ITAA 1997 307-230(1)(c)
ITAA 1997 307-230(1)(d)
ITAA 1997 307-230(2)
ITAA 1997 307-230(3)
ITAA 1997 307-230A
ITAA 1997 307-230A(1)(a)
ITAA 1997 307-230A(1)(b)
ITAA 1997 307-231
ITAA 1997 307-231(1)
ITAA 1997 307-231(1)(e)(i)
ITAA 1997 307-231(1)(e)(ii)
ITAA 1997 307-231(3)
ITAA 1997 960-265
ITAA 1997 960-285
ITAA 1997 995-1(1)
ITAR (1997 Act) 2021 307-230.01
ITAR (1997 Act) 2021 307-230.01(3)
ITAR (1997 Act) 2021 307-230A.02(1)
ITAR (1997 Act) 2021 307-230A.02(5)
Income Tax (Transitional Provisions) Act 1997 307-231(1)
Income Tax (Transitional Provisions) Act 1997 307-231(2)
RSA Regulations
SISA 10(1)
SISA 67A(1)
SISR Schedule 1 Pt 1 item 101
SISR Sch 1 Pt 1 item 102A
SISR Sch 1 Pt 1 item 103
SISR Sch 1 Pt 1 item 106
SISR 1.03(1)
SISR 1.05(4)
SISR 1.06(4)
Superannuation (Building a Stronger and Fairer Super System) Imposition Act 2026
Superannuation (Government Co-contribution for Low Income Earners) Act 2003 6(1)
Superannuation (Government Co-contribution for Low Income Earners) Act 2003 6(1)(da)
Superannuation (Government Co-contribution for Low Income Earners) Act 2003 6(1)(db)
Superannuation (Government Co-contribution for Low Income Earners) Act 2003 56
Other References:
Explanatory Memorandum to the Treasury Laws Amendment (2018 Superannuation Measures No. 1) Bill 2019
Explanatory Memorandum to the Treasury Laws Amendment (Building a Stronger and Fairer Super System) Bill 2026 and the Superannuation (Building a Stronger and Fairer Super System) Imposition Bill 2026
Copyright notice
© Australian Taxation Office for the Commonwealth of Australia
You are free to copy, adapt, modify, transmit and distribute material on this website as you wish (but not in any way that suggests the ATO or the Commonwealth endorses you or any of your services or products).
