

ATO Interpretative Decision
ATO ID 2005/60
Income Tax
Consolidation: MEC Consolidation: eligible tier-1 company de-registeredFOI status: may be released
Status of this decision: Decision Current
This ATOID provides you with the following level of protection:
If you reasonably apply this decision in good faith to your own circumstances (which are not materially different from those described in the decision), and the decision is later found to be incorrect you will not be liable to pay any penalty or interest. However, you will be required to pay any underpaid tax (or repay any over-claimed credit, grant or benefit), provided the time limits under the law allow it. If you do intend to apply this decision to your own circumstances, you will need to ensure that the relevant provisions referred to in the decision have not been amended or repealed. You may wish to obtain further advice from the Tax Office or from a professional adviser.
Issue
For the purposes of section 719-50 of the Income Tax Assessment Act 1997 (ITAA 1997), are A Co and B Co able to make the choice to consolidate a potential multiple entity consolidated (MEC) group by virtue of subsection 719-50(4) of the ITAA 1997 from 1 January 2003 notwithstanding that B Co has since been de-registered?
Decision
Yes. Under section 719-50 of the ITAA 1997, A Co and B Co are able to make the choice to consolidate the potential MEC group by virtue of subsection 719-50(4) of the ITAA 1997 from 1 January 2003 notwithstanding that B Co has since been de-registered. B Co is taken to have authorised A Co, the company that will be the head company of the MEC group, to make the choice to form a MEC group on behalf of B Co.
Facts
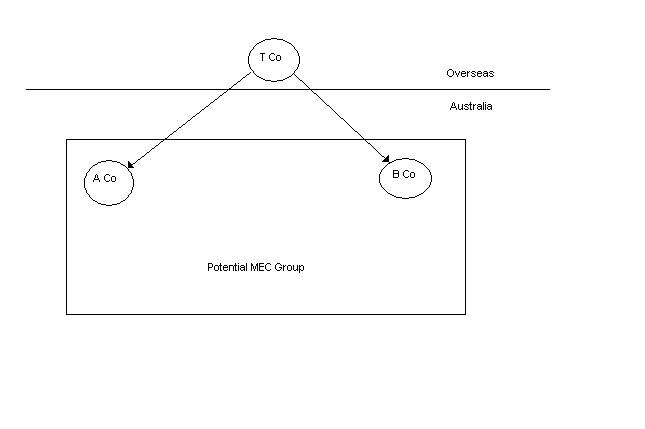
A Co and B Co are direct entry points for investment in Australia by T Co and were both eligible tier-1 companies.
On 1 January 2003 A Co and B Co comprised a potential MEC group.
B Co was de-registered late in 2004. Between 1 January 2003 and the date B Co was de-registered A Co and B Co were wholly owned subsidiaries of T Co, a company registered overseas.
Neither A Co nor B Co has previously been a member of a consolidated group or a MEC group.
A Co and B Co did not give the Commissioner a notice of choice to form a MEC group before B Co was de-registered.
Mr Y, a director of B Co before it was de-registered, has made a statutory declaration that B Co would have been a party to a choice to appoint A Co the provisional head company of a MEC group including A Co and B Co forming on 1 January 2003 if B Co had continued to exist.
A Co will give the notice of choice to the Commissioner on the day A Co lodges its return for the year ended 31 December 2003.
Reasons for Decision
Subsection 719-50(1) of the ITAA 1997 provides for two or more eligible tier-1 companies, as defined in section 719-15 of the ITAA 1997, in existence at the start of a particular day after 30 June 2002 to make a choice that a potential MEC group derived from those companies be consolidated on and after that day.
Where a company ceases to be an eligible tier-1 company before the choice is given to the Commissioner, subsection 719-50(4) of the ITAA 1997 may apply. Subsection 719-50(4) will apply if paragraphs 719-50(4)(a), 719-50(4)(b) and 719-50(4)(c) of the ITAA 1997 are satisfied. Paragraph 719-50(4)(a) will be satisfied if, as a result of the choice, an eligible tier-1 company will be the head company of the group. Paragraph 719-50(4)(b) will be satisfied if another eligible tier-1 company ceased to exist before the notice of the choice was given to the Commissioner. Paragraph 719-50(4)(c) will be satisfied if 'having regard to the relevant circumstances, it would be reasonable to conclude that the other company would have been a party to the choice if the other company had continued to exist.'
Paragraph 4.117 of the Explanatory Memorandum to New Business Tax System (Consolidation) Bill (No.1) 2002 does not specify what circumstances would be considered relevant for the purposes of paragraph 719-50(4)(c) of the ITAA 1997.
If paragraphs 719-50(4)(a), 719-50(4)(b) and 719-50(4)(c) of the ITAA 1997 are satisfied, an eligible tier-1 company that was de-registered can be taken to have authorised the eligible tier-1 company that will be the head company of the MEC group to make the choice on behalf of the de-registered company.
As B Co was not already a member of a consolidated group or a MEC group before it was de-registered, it could have made the choice under subsection 719-50(1) of the ITAA 1997 before it was de-registered.
The statutory declaration by Mr Y confirms that B Co would have been a party to the choice if B Co had continued to exist. Paragraph 719-50(4)(c) of the ITAA 1997 is therefore satisfied.
For the purposes of subsection 719-50(4) of the ITAA 1997, A Co can be taken to be authorised by B Co under paragraph 719-50(4)(d) of the ITAA 1997 to make the choice to form a MEC group on behalf of B Co.
Date of decision: 28 January 2005Year of income: Year ended 31 December 2003
Legislative References:
Income Tax Assessment Act 1997
section 719-15
section 719-50
subsection 719-50(1)
paragraph 719-50(4)(a)
paragraph 719-50(4)(b)
paragraph 719-50(4)(c)
paragraph 719-50(4)(d)
Other References:
Explanatory Memorandum to New Business Tax System (Consolidation) Bill (No. 1) 2002
Keywords
Choice to form
Consolidation - multiple entry consolidated group
ISSN: 1445-2782